Montreal Canadiens valued at C$5.4 billion
Sportico puts the Montreal Canadiens’ value up 15%. Brand strength and television rights help explain the growth in sports franchise valuations.
Published
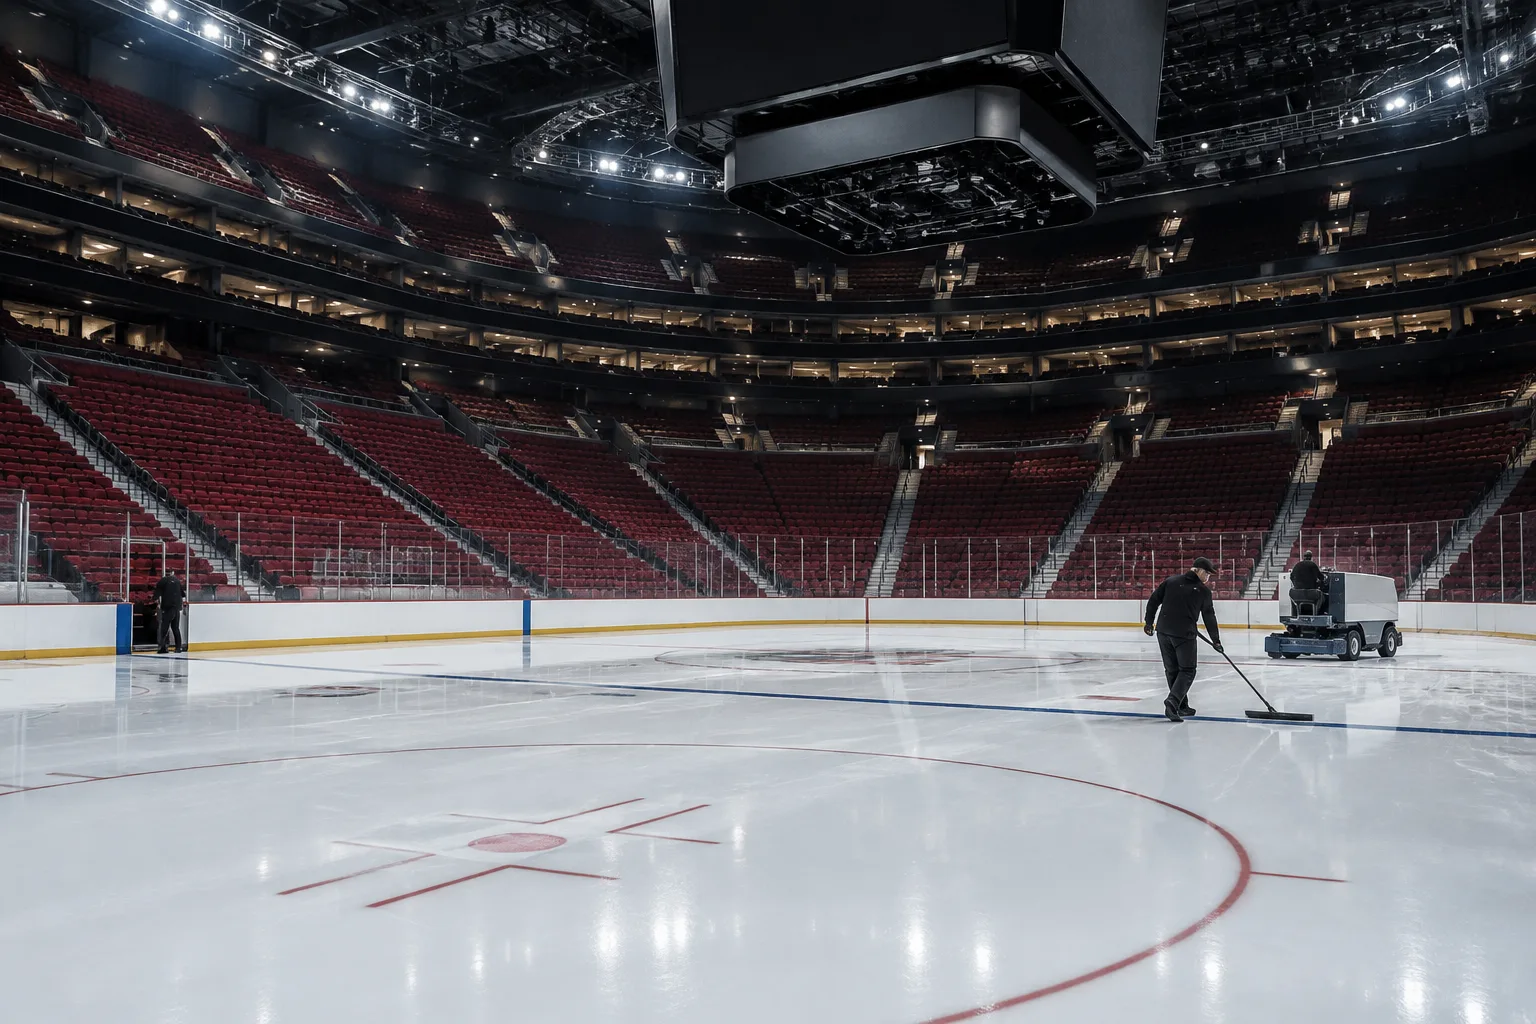
The Montreal Canadiens have reached an estimated value of C$5.4 billion, up 15% year on year. According to Sportico figures reported by La Presse on 29 September 2026, the club remains the third most valuable franchise in the National Hockey League (NHL). The increase highlights the importance of brand strength, media revenue and related business activities.
Montreal remains among the most valuable franchises
The Canadiens’ valuation is equivalent to US$3.8 billion. Ahead of them, the Toronto Maple Leafs retain the top spot in Sportico’s ranking, valued at US$4.8 billion, or C$6.8 billion. Their value rose by 13% over the year.
The New York Rangers remain in second place, with an estimated value of US$4.15 billion, up 14%. Montreal therefore still trails both organisations, although its annual percentage increase was slightly higher.
These figures are valuations, not announced sale prices. Sportico bases its calculations on interviews with bankers, investors, lawyers, team executives and owners. The distinction matters for those in the franchising sector: an estimated valuation is not the same as an organisation’s turnover or profit.
Montreal’s revenue rises by 9%
The Montreal organisation generated revenue of US$364 million in the 2025–2026 season, according to Sportico. This was up from US$335 million the previous season, an increase of 9%. The Canadiens’ season extended to late May thanks to their play-off run.
Across the NHL, the 32 teams generated an estimated US$8.3 billion in revenue during the same season. The average was US$259 million per club, putting Montreal’s revenue above the league average.
However, the figures cover more than hockey alone. The calculation also includes events unrelated to NHL hockey, notably concerts and other events held in arenas owned or managed by the organisations.
This detail helps put the results into context: the reported revenue covers a range of activities, not just match ticket sales. On its own, it does not establish how profitable each activity is.
Brand strength and television rights take centre stage
In comments broadcast by Radio-Canada on 30 September, Éric Brunelle highlighted the strength of the Canadiens’ brand. He explained that it helps the club sell merchandise and maximise the value of its television rights.
His analysis places ticket sales within a broader mix of revenue streams. It provides additional context for Sportico’s figures, without offering a numerical breakdown of the revenue generated by each of the club’s activities.
Broadcasting rights are also an important part of the league’s outlook. According to Sportico, revenue across the organisations, already up 4.4% year on year, could grow by 8–9% during the 2026–2027 season as the new Canadian broadcasting contract takes effect.
La Presse notes that Rogers Communications signed an agreement worth $11 billion with the NHL the previous year, covering a further 12 years. The anticipated revenue increase remains a forecast, distinct from the results already reported for 2025–2026.
A valuation that goes beyond results on the ice
The average NHL franchise is worth US$2.43 billion, according to Sportico. That represents an increase of 16% compared with 2025 and 160% over five years. The Canadiens’ rising value is therefore part of a broader trend.
The valuations also take account of the organisations’ property assets and related operations, including their American Hockey League teams and the arenas in which they play. The value assigned to a club therefore reflects more than its brand or sporting performance alone.
For international readers considering Canada’s franchising market, these figures chiefly serve as a reminder of how valuations should be assessed, rather than as a direct benchmark for a commercial franchise network. Key takeaway: before using a valuation as a reference point, check the currency, the period covered, the assets included and the distinction between recorded revenue and projected growth.