Franchising in Taiwan: Handling Uniform Invoices and Business Tax on Franchise Fees
Even when a franchise fee is collected as a one-off payment or includes equipment and raw materials, invoicing and tax reporting obligations still apply. Before recruiting franchisees, franchisors should clarify what each transaction covers, who receives payment and how Taiwan’s uniform invoices will be issued.
Published
When opening an existing business to franchising, franchisors often focus first on brand licensing and training, treating the franchise fee as a general ‘cooperation payment’ without putting invoicing arrangements in place. In Taiwan’s franchise market, transparent charging is about more than the quoted price: it also means making clear who receives payment, who issues the invoice and whether the accounts accurately reflect the transaction. This article focuses on the tax procedures involved in collecting franchise fees for the first time.
1. Identify what the franchise fee actually covers
The Ministry of Finance’s National Taxation Bureau of Kaohsiung explains that a one-off initial franchise fee charged by a franchisor to a franchisee constitutes a sale of services. The franchisor must therefore issue a uniform invoice — Taiwan’s prescribed tax invoice — and report and pay business tax as required. If the fee also covers business tools, equipment or raw materials, the transaction includes sales of both goods and services. Calling the whole amount a ‘franchise fee’ does not remove the invoicing obligation.
Franchisors can start by preparing an internal breakdown of the charges:
- Brand and business know-how licensing: specify the scope and duration of the licence.
- Pre-opening training and preparation services: specify the services and delivery arrangements.
- Equipment and tools: establish whether these are being sold, hired out or made available for use.
- Initial stock and raw materials: list the items, quantities and delivery arrangements.
This breakdown does not mean that every item must have a separate price or invoice. Its purpose is to help accounting staff determine the correct treatment based on the actual transaction. A charge’s contractual label alone is not a basis for treating income received in exchange for goods or services as outside the scope of business tax.
2. Align quotations, contracts and the entity issuing invoices
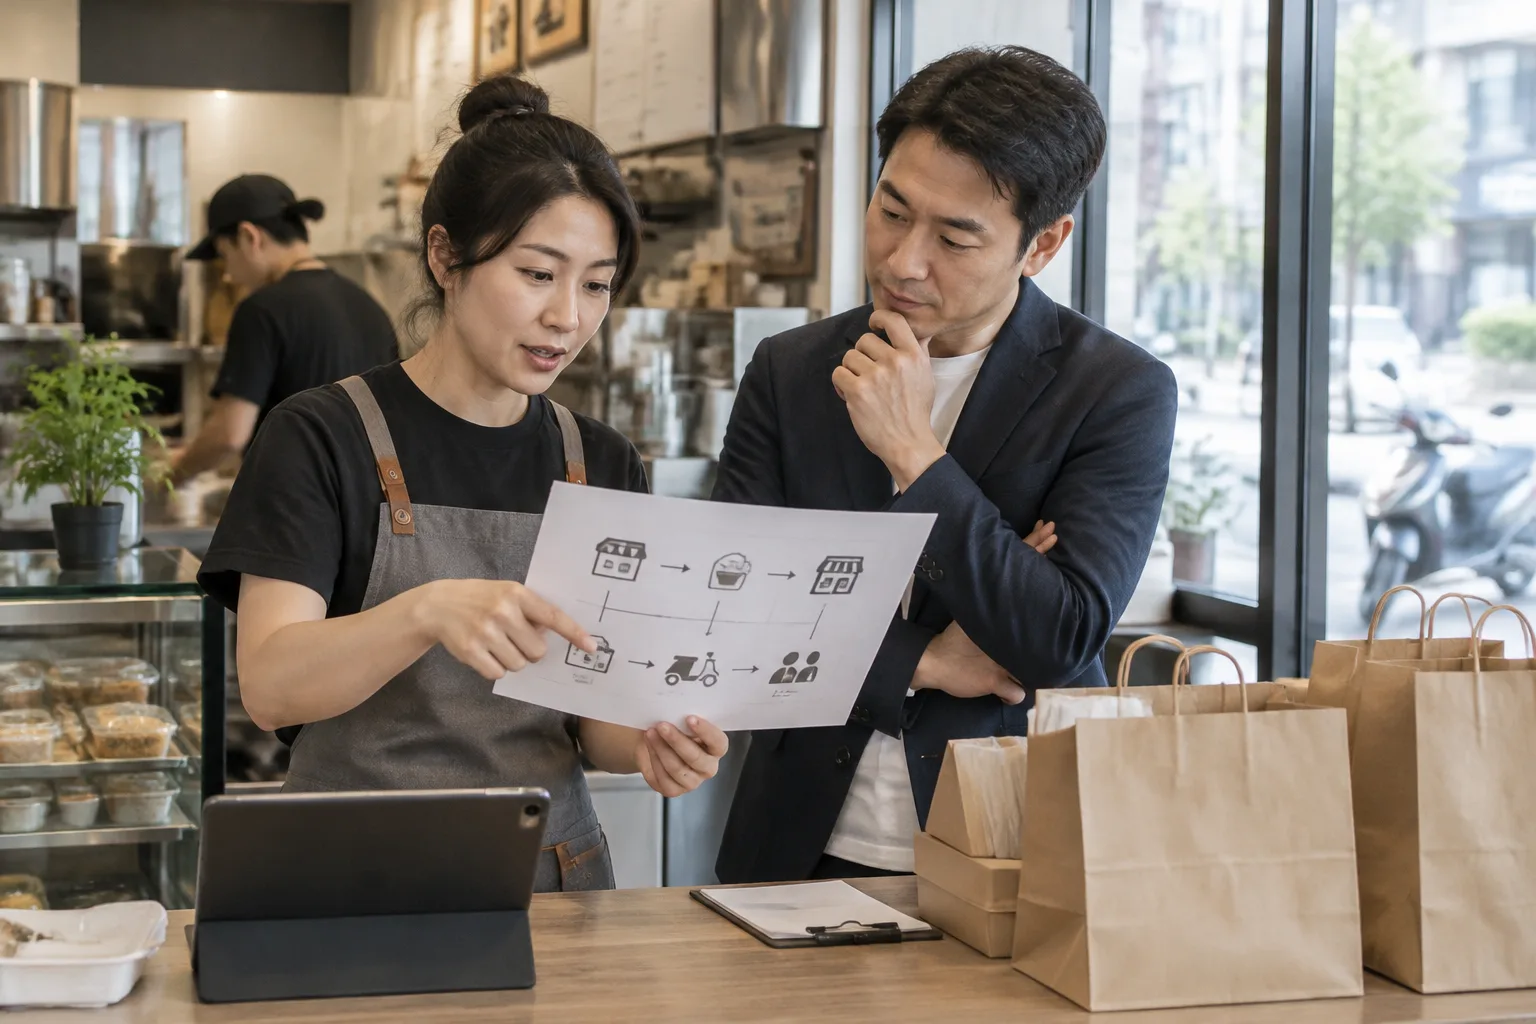
Before recruiting franchisees, the people responsible for operations, finance and contracts should jointly confirm a schedule of charges. For each item, record what the transaction covers, who receives payment, who issues the invoice, the payment arrangements and whether the quoted price includes tax. The total shown to applicants should match the contract and the actual payment requirements.
For example, if the franchise package includes a coffee machine, first establish whether the franchisor buys it and resells it to the franchisee, or whether the franchisee buys it directly from the equipment supplier. These arrangements involve different transaction and invoicing relationships. The fact that the supplier delivers the machine does not, by itself, mean that the supplier should invoice the franchisee. Any arrangement for collecting or making payments on another party’s behalf should also be checked by accounting staff against the facts, rather than relabelled after the event.
In particular, recruitment staff should not promise applicants a discount if they agree to forgo an invoice. A legally required uniform invoice is not an optional service that the parties can agree to waive. If an applicant has not yet completed business registration, first confirm the parties to the transaction and payment, then ask accounting staff to arrange the correct invoice details. Do not casually use another company’s Unified Business Number, Taiwan’s business identification number.
3. Connect tax arrangements with franchise disclosure
Taiwan does not have a single dedicated franchise law governing every aspect of franchising, but franchise recruitment is still subject to specific rules. The Fair Trade Commission has issued its Disposal Directions (Guidelines) on the Business Practices of Franchisors, which operate alongside the Fair Trade Act to address information imbalances in franchise transactions. Invoicing and business tax, meanwhile, must comply with legislation including the Value-added and Non-value-added Business Tax Act.
The guidelines require franchisors to disclose important information about fees payable before operations begin and during the operating period, including the amounts or estimated amounts payable to the franchisor or persons it designates. In principle, this information should be provided ten days before entering into a franchise or preliminary franchise relationship, within a period considered reasonable in the circumstances, or within a period agreed by both parties. A breach that is sufficient to affect trading order may violate Article 25 of the Fair Trade Act.
A quotation should therefore not present a seemingly all-inclusive franchise fee, only for previously unexplained tax to be added when payment is due. In practice, the fee schedule should clearly state whether prices include or exclude tax and make the total amount payable easy for applicants to understand. This is a way to improve disclosure clarity; it should not be described as a specific tax disclosure form mandated by the guidelines.
4. Establish checks from payment collection through to tax filing
After each franchise agreement is signed, finance staff should obtain the contract, fee breakdown, details of the parties to the transaction, payment records and relevant delivery or service records. They should then determine when invoices must be issued under the applicable rules. Do not assume that no invoice is needed until the outlet opens, or routinely wait until every payment has been received.
Before each tax return is filed, reconcile three sets of records: bank and other payment receipts, invoices issued and sales recorded in the accounts. Document the reason for every discrepancy and assign someone to follow it up, so that money already received does not remain indefinitely in a temporary receipts account. If the contract is later terminated or fees are refunded, check the corresponding invoice treatment and any sales return or allowance adjustments. Refunding the money without adjusting the supporting documents is not enough.
If past failures to issue invoices or report sales come to light, ask an accountant or tax professional to investigate promptly. Article 48-1 of the Tax Collection Act provides a penalty exemption mechanism for voluntary supplementary reporting and payment. However, eligibility is subject to conditions, including the absence of a prior report of the violation or a relevant investigation, and interest is payable. It does not mean that issuing an overdue invoice at any time will automatically avoid penalties.
Practical takeaway: Before collecting the first franchise fee, run a simulated transaction through the full sequence: quotation, contract signing, payment collection, invoicing, bookkeeping and tax filing. Start charging only once every step is aligned with the underlying transaction and has a clearly identified person responsible.