Franchising a Business in Taiwan: Setting Out Exit Stock Buyback and Equipment Disposal Arrangements
Who takes responsibility for unsold stock and specialist equipment when a franchise ends? Before recruiting franchisees, franchisors should set out stocktaking, buyback eligibility, valuation and handover procedures so applicants can understand the costs of leaving.
Published
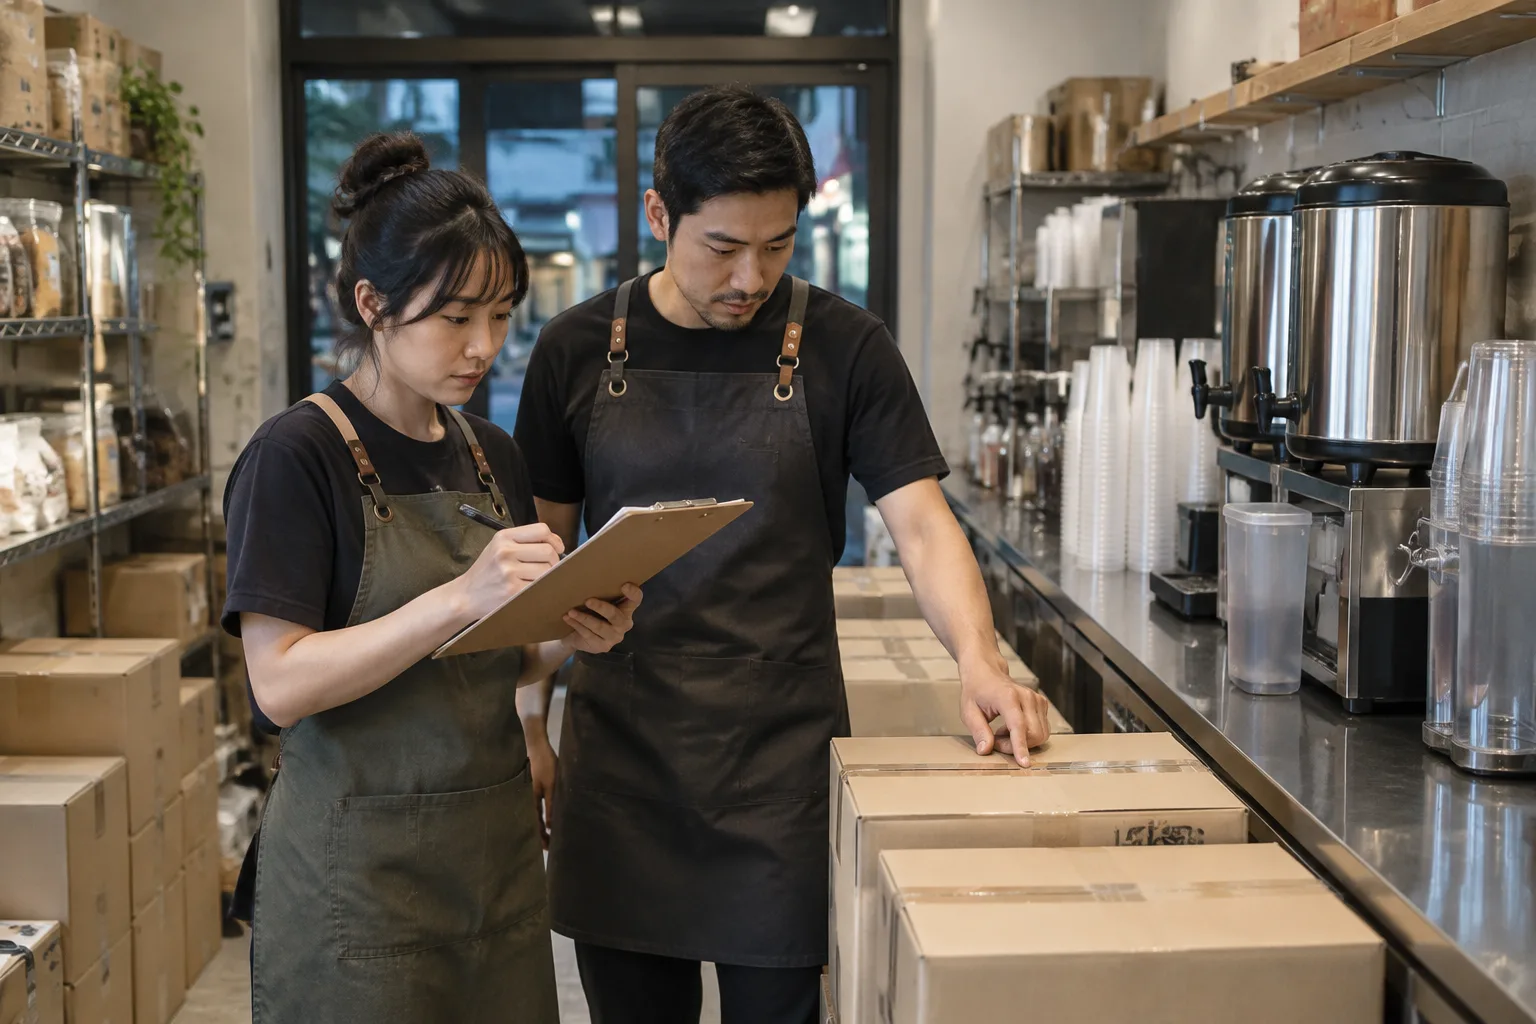
Opening an existing business in Taiwan to franchising involves more than calculating the stock and equipment needed to launch each outlet. It also means answering a question in advance: what happens to the remaining assets when the agreement expires or ends early? Branded packaging, food with a limited shelf life and specialist machinery can be particularly difficult to resell. Clear exit arrangements help reduce disputes across the franchise network and allow prospective franchisees to assess the true investment risks.
1. Clarify the legal requirements and buyback commitments
Taiwan has no single, comprehensive franchise statute, but franchise transactions are subject to specific regulatory guidance. The Taiwan Fair Trade Commission’s Guidelines on the Business Conduct of Franchisors identify key franchise information, including the conditions and procedures for amending, terminating and rescinding franchise agreements. Concealing material transaction information in a way that is sufficient to affect trading order may engage Article 25 of the Fair Trade Act. Contractual performance and property rights must also be assessed under the Civil Code and other relevant legislation.
These guidelines do not impose a blanket requirement on franchisors to offer an exit buyback. Franchisors should assess what they can afford to undertake and clearly distinguish between a guaranteed buyback, a conditional buyback and no buyback at all. They should not promise help with an exit during recruitment, only to explain after signing that this means providing a list of second-hand buyers.
These arrangements should form part of the key pre-contract information and the contract schedules, rather than being left for negotiation at exit. Under the guidelines, key information should generally be provided ten days before entering into a franchise or preliminary franchise relationship, or within a period agreed by both parties. Do not wait until non-refundable fees have been collected to explain buyback restrictions. A lawyer familiar with franchise transactions in Taiwan should review the specific terms.
2. Classify assets by ownership and potential for reuse
Before preparing an exit inventory, establish who owns each item. Equipment bought by the franchisee, lent to the outlet by the franchisor or leased from a third party cannot all be handled in the same way. Invoices, lease documents, equipment identification numbers and delivery records should be organised from the outset.
Consider dividing assets into four categories:
- General stock: Assess whether unopened ingredients or products with traceable origins, stored under the required conditions, can be put back into circulation.
- Brand-specific materials: Specify how cups, bags, uniforms and display materials bearing trade marks must be collected, de-branded or destroyed. Do not assume they can be freely resold.
- Franchisee-owned equipment: State whether the franchisor will purchase it or merely help introduce potential buyers. Assistance with a sale is not a guarantee that it will sell.
- Leased or borrowed equipment: Return it in accordance with the owner’s terms, dealing separately with dismantling costs, rent arrears and liability for damage.
Fit-out works and fixtures should be listed separately. Even where the franchisee paid for them, dismantling or removal may be restricted by the premises lease and its reinstatement obligations. The franchise agreement alone cannot determine what is permitted.
3. Make buyback eligibility and valuation rules calculable
A promise to buy back assets ‘at a reasonable price’ may sound flexible, but it can easily lead to disputes. The contract schedule should specify eligible items, supporting documents, the pricing basis, deductions and grounds for rejection, so franchisees know how assets will be treated before purchasing them.
Stock eligibility can depend on whether items are unopened, packaging is intact, sufficient shelf life remains and storage records are available. The franchisor should set standards appropriate to each product, rather than introduce new restrictions on the day of exit. Any differences in treatment between normal expiry, termination by mutual agreement and termination for breach must also be stated in advance. A general clause saying that ‘the franchisor reserves the right to make the final decision’ is no substitute for specific rules.
Equipment valuations can take account of purchase documents, age, maintenance records and current condition. If a depreciation formula is used, explain the calculation. If valuation is based on second-hand market prices, specify the sources of quotations and a review procedure for disagreements. An asset’s depreciated book value does not necessarily reflect its actual resale price.
Also explain who pays for dismantling, transport, inspection and cleaning, and whether quoted prices include tax. A franchisor promising a buyback should assess its storage capacity, available funds and ability to redistribute the assets in advance, rather than make commitments it cannot fulfil.
4. Establish stocktaking, handover and payment procedures
Exit arrangements should involve more than a single statement showing a final settlement figure. Franchisors can use the following process, with completion deadlines agreed to suit the outlet’s circumstances:
- Submit an inventory: The franchisee provides item descriptions, quantities, batch details, equipment identification numbers and proof of ownership.
- Conduct a joint stocktake: Both parties check the condition of the assets and take photographs, listing disputed items separately.
- Confirm valuations: Record the quantity accepted, unit price, deductions and charges for each item, and obtain written confirmation.
- Complete the handover: Record the collection date, carrier and person signing for receipt. Specify when responsibility for safekeeping and transport risk transfers.
- Settle payment: Provide an itemised settlement statement, pay the buyback amount as agreed and retain handover and payment records.
Do not simply include unconfirmed contractual penalties among buyback deductions. Any set-off against outstanding debts must have a proper basis, with the nature of each amount and its calculation clearly stated. For branded materials that are not bought back, provide practical disposal instructions and evidence requirements. Franchisees should not be left unable to sell the materials and unsure who should receive them.
Practical takeaway: Before recruiting, use the asset inventory of an existing outlet to run through a simulated exit. For every item, answer four questions: who owns it, who will take it, how will it be valued and when will payment be made? Any point that still depends on last-minute negotiation should be turned into clear contractual terms before accepting the first franchisees.