VeloBank plans 180 franchise branches by the end of 2026
VeloBank is preparing around 20 franchise branch openings in Poland. It is seeking premises of around 50 sq m, including sites near residential areas and shopping centres.
Published
VeloBank aims to expand its franchise network in Poland to 180 branches by the end of 2026. It is preparing around 20 new openings and is in talks with entrepreneurs interested in becoming partners. For those considering a franchise in Poland, this signals further opportunities to provide financial services through local branches. The bank’s plans cover both major urban areas and smaller towns.
Around 20 openings planned for the end of the year
The expansion target was outlined by Renata Kurnyta-Kowalska, Director of VeloBank’s Partner Network Department. According to a report published by PropertyNews on 26 October 2026, the bank intends to reach 180 franchise branches by the end of the year. The report put the number of franchise branches at the end of October at more than 160.
The bank expects to open around 20 additional branches. Talks with prospective partners are already under way, so the announcement concerns not only the network’s target size but also openings in preparation. However, the stated target should not be confused with the number of branches already serving customers: reaching 180 branches remains a goal to be achieved by the end of 2026.
This distinction matters for entrepreneurs considering joining the network. The expansion announcement indicates that the bank is looking for new partners, but it does not mean that any proposed location will be available. Prospective partners should establish which towns, cities and areas are still under consideration, and what opening timetable the bank envisages for their particular branch.
Premises sought: around 50 sq m with regular footfall
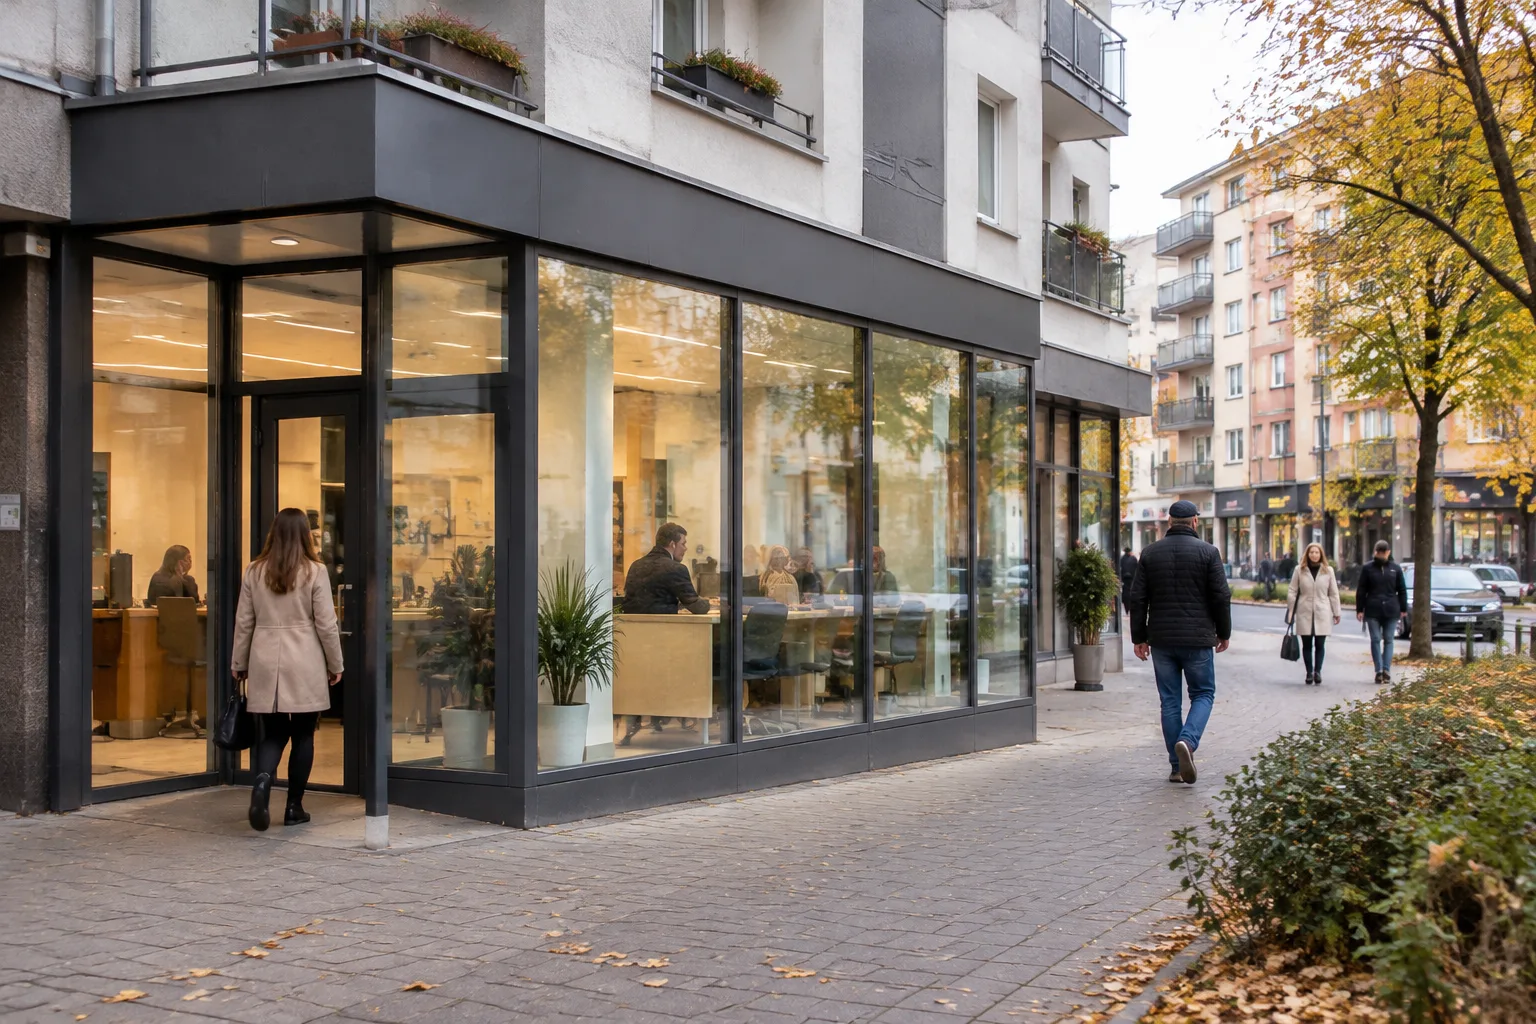
VeloBank is looking for premises of around 50 sq m. Its preferred locations include sites near residential developments, shopping centres and busy pedestrian routes. These provide clear pointers for both prospective franchisees and property owners interested in offering premises to the bank.
It is important to interpret these criteria carefully. Being near a shopping centre does not necessarily mean being inside one. Likewise, the indicative size of around 50 sq m does not mean that every property of that size will be suitable. Floor area and surroundings are a starting point for discussions, not confirmation that the bank will approve a property.
Before submitting a property, it is worth preparing a description of its location, floor area and immediate surroundings. Highlighting nearby housing, retail facilities and pedestrian routes will be useful, as these match VeloBank’s stated search criteria. However, the assessment of a specific address should be left to the bank, rather than assuming that proximity to a residential area meets all its requirements.
Expansion is not limited to large cities
The bank is expanding its network in both major urban areas and smaller towns. This is important for prospective partners: the announced expansion is not presented as a project solely for the largest urban markets. Proposed locations could therefore come from towns and cities of different sizes.
This does not mean, however, that a new opening is planned in every town or city. The statement about the scope of expansion describes a general direction, rather than a list of approved addresses. Entrepreneurs should therefore first check whether the bank is interested in their area before making commitments to lease or fit out premises.
For prospective franchisees, two points are particularly relevant: the bank is seeking additional partners and has also outlined the characteristics of the properties it wants. This makes it easier to prepare for an initial discussion. Candidates can present not only their interest in running a branch but also a specific location that matches the stated criteria.
What to check before deciding to become a partner
The announcement of new openings provides information about network expansion, not a full account of the franchise’s financial terms. The number of planned branches alone is not enough to assess the profitability of an individual outlet. Similarly, a small floor area should not be taken as evidence of low start-up costs.
Before making a decision, prospective partners should ask the bank for detailed terms: the required financial contribution, how partners are remunerated, how fit-out costs are shared, staffing responsibilities and the support available for opening a branch. The set-up timetable and property approval criteria also need clarification. These are points to investigate, not confirmed features of VeloBank’s offer.
Property owners and prospective franchisees should also separate the assessment of the premises from the decision to run the business. An attractive address may strengthen a proposal, but it is no substitute for reviewing the agreement and costs. Practical takeaway: first confirm VeloBank’s interest in the proposed location and establish the financial terms, then make commitments relating to the premises.