Student Accommodation and Co-living in the UAE: Signals for the Franchise Sector
Cavendish Maxwell sees opportunities in student accommodation and co-living in the UAE — trends worth examining when assessing potential franchise locations.
Published
The outlook for property in the UAE is moving beyond luxury homes and branded residences. In an article published by Franchise Kuwait on 30 September 2026, Cavendish Maxwell argues that student accommodation, co-living and other professionally managed models deserve greater attention. For the franchise sector, the value of this outlook lies in understanding emerging residential settings, rather than treating it as an announcement of ready-made franchise opportunities.
An expected shift in accommodation patterns
According to Cavendish Maxwell, student accommodation and senior living will play a pivotal role in shaping the property market across the Gulf Cooperation Council (GCC) countries over the next decade. The company also identifies serviced accommodation, co-living, private members’ clubs, shared ownership and other professionally managed residential developments as leading future investment opportunities in the region.
The company links these expectations to the increasingly blurred boundaries between living, staying, working and socialising. Its vision goes beyond changing the type of residential unit on offer: it encompasses models that bring several functions together within a residential setting. This is an important distinction when interpreting the report: it describes an anticipated property trend, not the opening of specific developments or the signing of new commercial agreements.
The company notes that luxury has dominated the Gulf’s residential and hospitality sectors for much of the past decade. Branded residences and five-star hotels, alongside mixed-use developments, have helped establish Dubai, Abu Dhabi and Riyadh on the global investment map. It expects the next phase to be more varied, with a shift towards different forms of shared living, driven by market fundamentals and growing demand.
Student accommodation comes into focus in the UAE
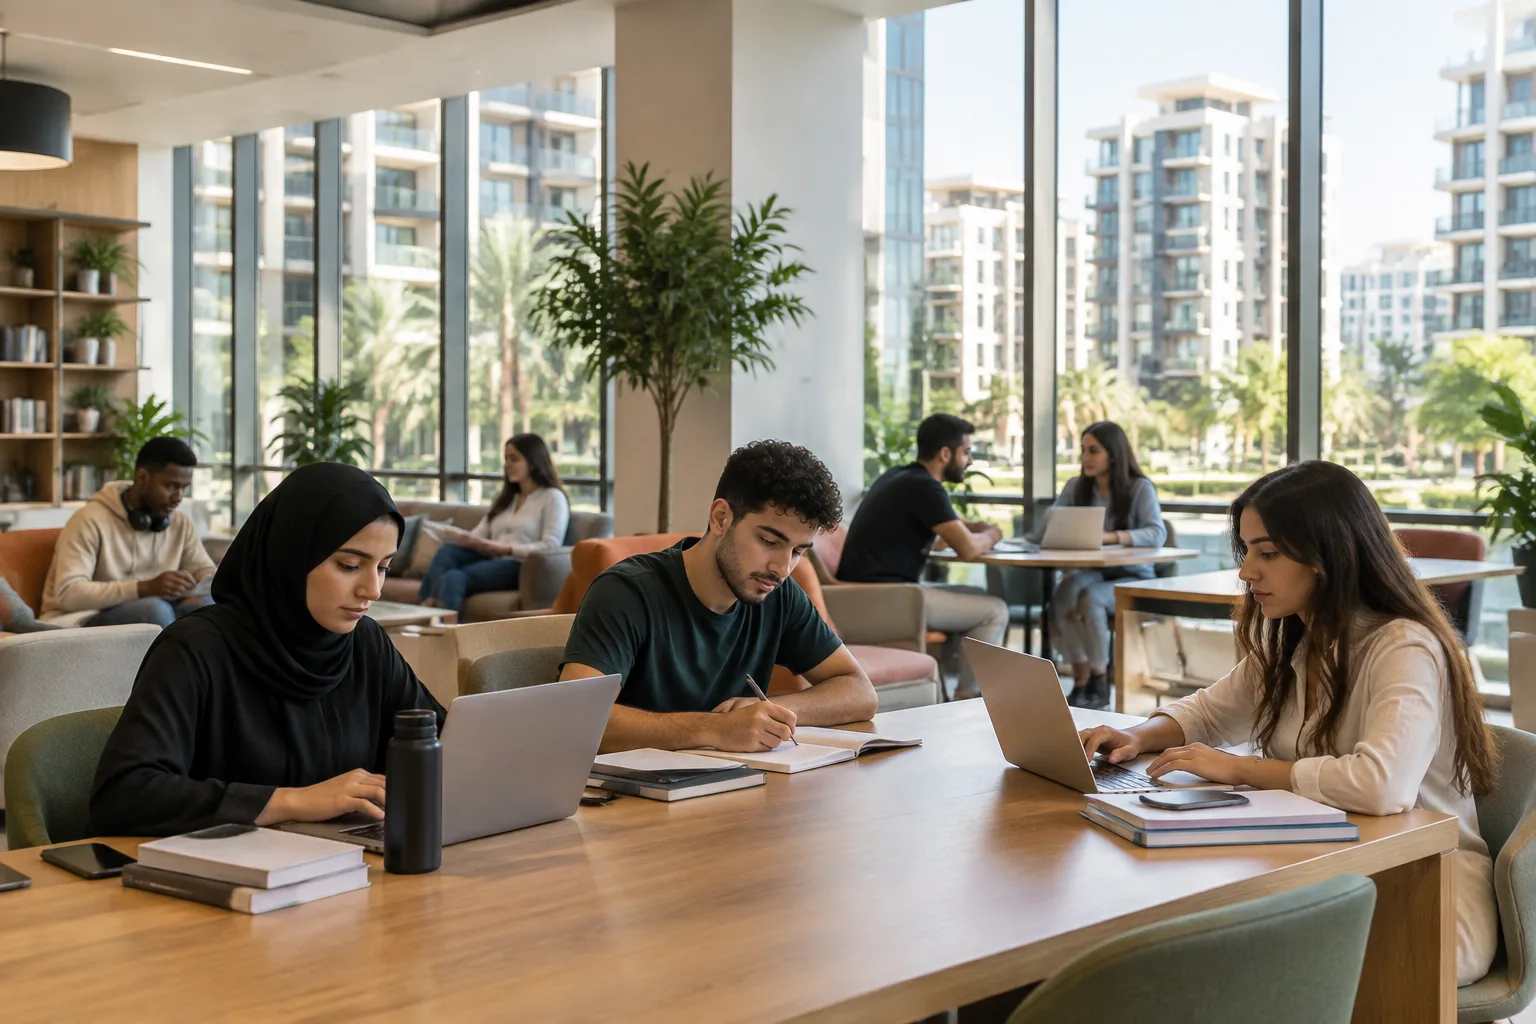
The UAE provides a clear example in the company’s assessment of student accommodation opportunities. Cavendish Maxwell points to the expansion of higher education, a growing university ecosystem and increasing ambitions to attract more students from the Middle East, Africa, Asia and elsewhere. As this population grows and becomes more international, the company sees an opportunity to develop accommodation tailored to its needs.
The needs identified in the research include community living, security, amenities, technology and study spaces. This makes clear that the opportunity is not simply to provide somewhere to sleep, but to develop professionally managed accommodation suited to student life. However, the report does not provide figures for the number of units required, occupancy rates or prices in the UAE.
The franchise sector should therefore distinguish between a trend worth monitoring and a feasibility study for a particular location. The article does not announce a brand’s entry into university accommodation, nor does it identify services to be offered there through franchising. Its main value remains in drawing attention to a group of users and a set of housing needs that the company expects to grow and diversify.
Dubai and co-living: interest without detailed figures
Cavendish Maxwell makes a specific point about co-living, arguing that it deserves more attention, particularly in Dubai. This observation forms part of a broader view of the overlap between living, working and socialising. It is not an announcement of a new development in the emirate or a numerical forecast of the size of the co-living market.
At the same time, the company does not expect branded residences to disappear. It sees them remaining an important part of the market, noting the Middle East’s leading position in both existing developments and those under development. The anticipated diversification therefore means a wider range of models, rather than the wholesale replacement of one model by another.
A further distinction matters here: describing a residence as branded does not, in itself, establish that it operates under a franchise agreement. Nor does professional property management automatically determine the commercial relationship between an owner and an operator. The published article provides no contractual details that would allow these models to be classified as specific franchise arrangements.
What can the franchise sector learn?
The practical value of this outlook is that it broadens the questions asked when assessing a location. When considering a business near a student community or a co-living building, an investor can ask who actually uses the area, what facilities are available, what residents need and what conditions govern access to the site. These are suggested due diligence questions, not market findings established by the published article.
The forecasts do not provide a sufficient basis for judging a business’s profitability or the suitability of a particular brand. They contain no data on spending, daily footfall or rental costs in these settings. Moving from monitoring a property trend to deciding to open a franchise therefore still requires location-specific information and verification of operating conditions.
Practical takeaway: Include student accommodation and co-living among the locations worth investigating in the UAE, but do not treat forecasts of growth as a guarantee of demand. Start with actual development-level data, then assess the brand’s suitability and residents’ needs before committing.