Opening stock for a franchise: ownership, valuation and shortages
Before buying a franchise, establish who owns the stock, how it will be valued and who will pay for shortages and expired products.
Published
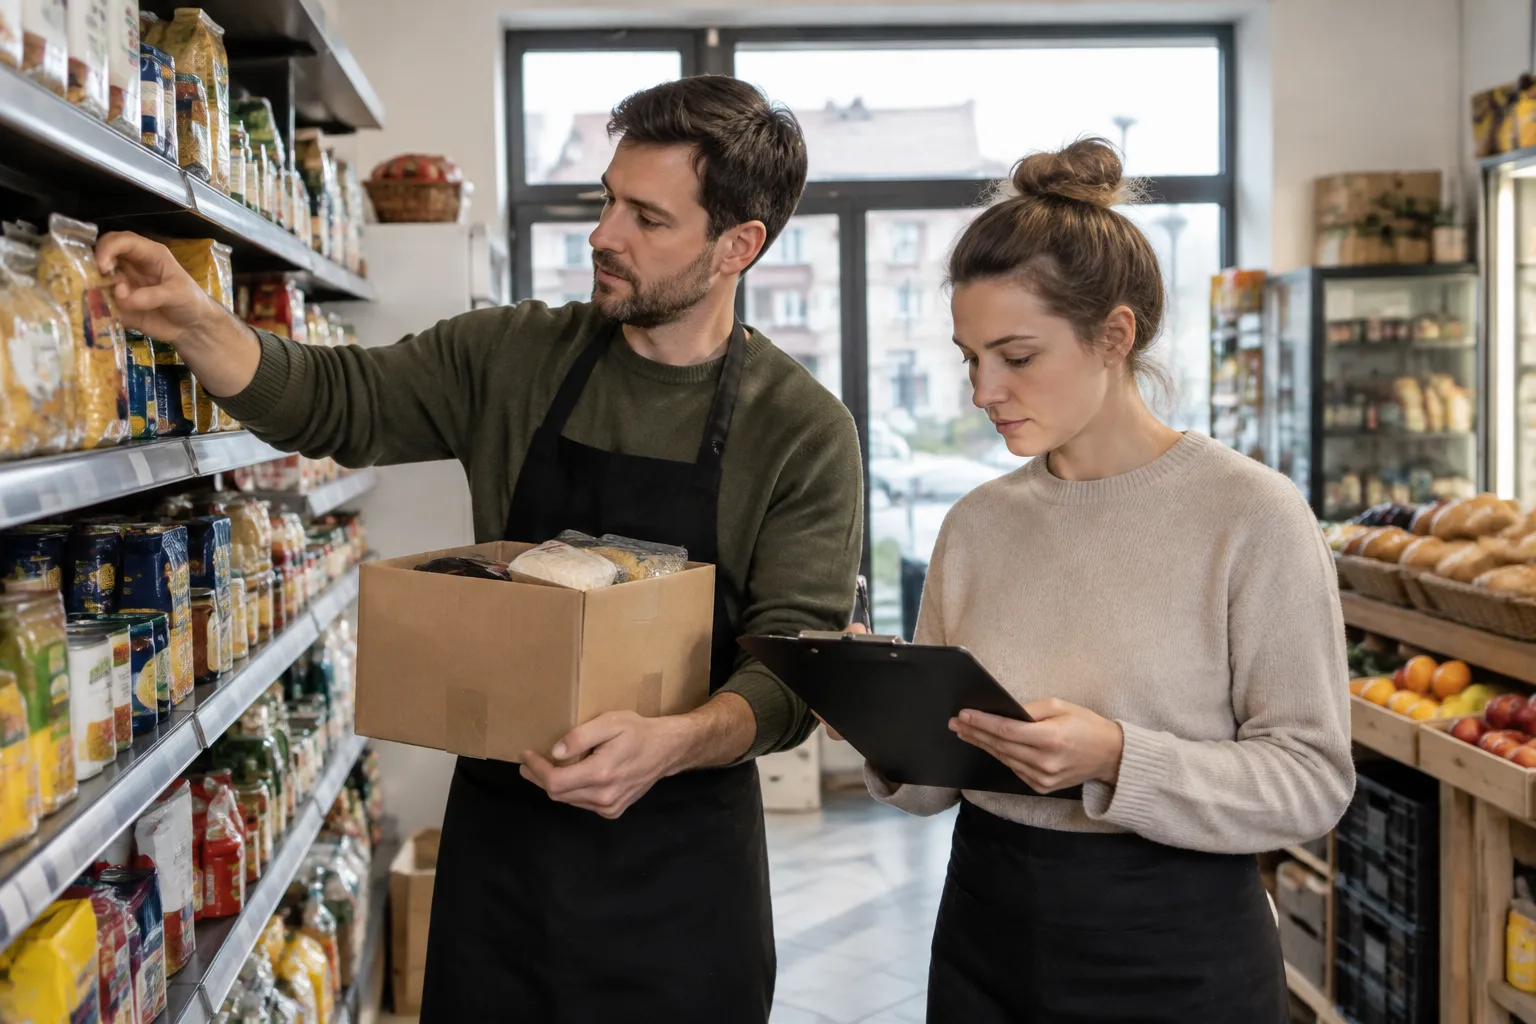
Full shelves do not necessarily mean assets you are buying along with a franchise outlet. The goods may belong to the outgoing operator, the franchisor or a supplier, and the payment arrangements affect both the cash you need and your liability for losses. When joining a franchise network, check the stock as carefully as the agreement itself. The key arrangements should be documented before you pay any money or take over the premises.
1. Establish whether you are buying the goods or merely holding them
Start with a simple question: who owns each product category on the day you take over the outlet? Being told that the goods are “network stock” is not enough. A logo on the packaging, a delivery invoice and an entry in the stock management system do not necessarily establish the same legal ownership.
You may be buying stock on your own account or receiving goods owned by someone else to sell under an agreed arrangement. Several models may operate within a single outlet. Ask for a breakdown covering:
- the owner of the goods and the document establishing the basis on which they are being handed over;
- when ownership and the risk of accidental loss pass to you;
- the payment deadline and method;
- arrangements for dealing with unsold products;
- any retention of ownership until payment has been made.
When buying an existing outlet, check that the seller is actually entitled to sell all the stock. Goods owned by head office should not simply be included in the price of the outgoing franchisee’s assets without clarification. Handing over the keys does not resolve these issues.
2. Agree the valuation and assess the cash implications
The stock value shown in the system may not reflect what it is reasonable to pay for the goods. First, establish the valuation basis: purchase price, price after discounts or another agreed value. Clarify whether the figures include or exclude VAT and how the transaction will be documented.
Separate stock in good, saleable condition from damaged, incomplete or seasonal products and those with a short remaining shelf life. For each category, agree whether to accept it at the stated price, reduce the price or exclude it from the purchase. Do not assume that head office will later take back unsold stock unless the agreed terms provide for this.
Also ask for the stock movement history. A large quantity of an item may reflect preparation for demand, but it may equally indicate products that have struggled to sell for some time. Compare delivery dates with actual sales of individual items.
Your opening budget should account not only for the cost of the initial stock, but also for when payment is due and the cost of replenishment. If you have to pay before you sell the products, you will need working capital. Check the timing and rules for VAT accounting with your accountant too; do not treat a future VAT deduction as cash available immediately.
3. Carry out a joint stocktake at handover
Before taking over, agree a counting procedure with the person handing over the goods and, where necessary, with head office. The safest approach is to base the final settlement on verified physical stock rather than solely on an earlier stock report.
The handover record should state the date and time, the participants, product codes, quantities, units of measurement, condition and agreed values. Include batch numbers and expiry dates where relevant. Identify third-party goods separately so they are not confused with the assets you are buying.
Agree how sales, deliveries and returns will be recorded during the count. Without a clear rule, some discrepancies may result from stock movements rather than actual shortages. Photograph any damage and list disputed items in an appendix.
Do not sign an unqualified declaration confirming that all stock is correct if you have not been able to check it. Agree a deadline for reporting discrepancies that could not be detected at handover, how evidence should be submitted and how the final settlement will be adjusted. It is also worth specifying who will resolve disputes and when any overpayment will be refunded.
4. Allocate responsibility for shortages and losses
Ownership of goods and liability for them are separate issues. You may be liable for products entrusted to you even though they are not your assets. Before signing the agreement, check when you assume responsibility and how the amount of any loss will be assessed.
Discuss theft, damage in transit, refrigeration failure, expired products and the recall of a defective batch separately. Each event may require different evidence and a different procedure. Ask who reports the loss, secures the products and authorises their disposal.
Do not assume that head office’s insurance policy automatically protects your outlet. Check the scope of cover, the excess, exclusions and whether it covers goods owned by other parties. Negotiate the right to check supporting documents before you are charged for a shortage, as well as an exclusion of liability for shortages arising before handover.
5. Distinguish contractual arrangements from accounting obligations
Poland has no separate, comprehensive statutory framework for franchising. A franchise agreement is an innominate contract — one not defined as a specific contract type in legislation — based on the principle of freedom of contract under Article 353¹ of the Polish Civil Code. Stock transactions are subject to the relevant civil, tax and accounting rules, depending on the business arrangement and the bookkeeping system used.
A handover record does not automatically replace a required physical stocktake. Businesses keeping a Polish tax revenue and expense ledger must include third-party goods held on their premises in the stocktake, but must not assign them a value; the owner must be identified. If you use another accounting system, agree the appropriate treatment with your accountant.
The practical takeaway: before paying for stock, agree three things: who owns it, what it is really worth and who bears the cost of discrepancies. Confirm these points in the agreement and a joint handover record.
Sources
- Umowa franczyzy – co powinna zawierać? Sprawdź
- Franczyza - DZP
- Franczyza jako inwestycja. Rzeczywisty koszt franczyzy, analiza umowy i zakup działającego punktu
- Franczyza | Dudkowiak & Putyra
- Umowa franczyzy a spis z natury - Poradnik Przedsiębiorcy
- O konieczności regulacji prawnej umowy franczyzy
- PRZEDSIĘBIORCA W SYSTEMIE FRANCZYZOWYM
- Kodeks Dobrych Praktyk dla Rynku Franczyzy