Franchising an Existing Business: Allocating the Costs of Unsold Stock, Waste and Returns
The cost of unsold and expired products can make or break franchisee profitability. This article explains what to put in place before recruiting franchisees, from testing in company-owned outlets to setting return conditions, recording disposals and reflecting the arrangements in contracts.
Published
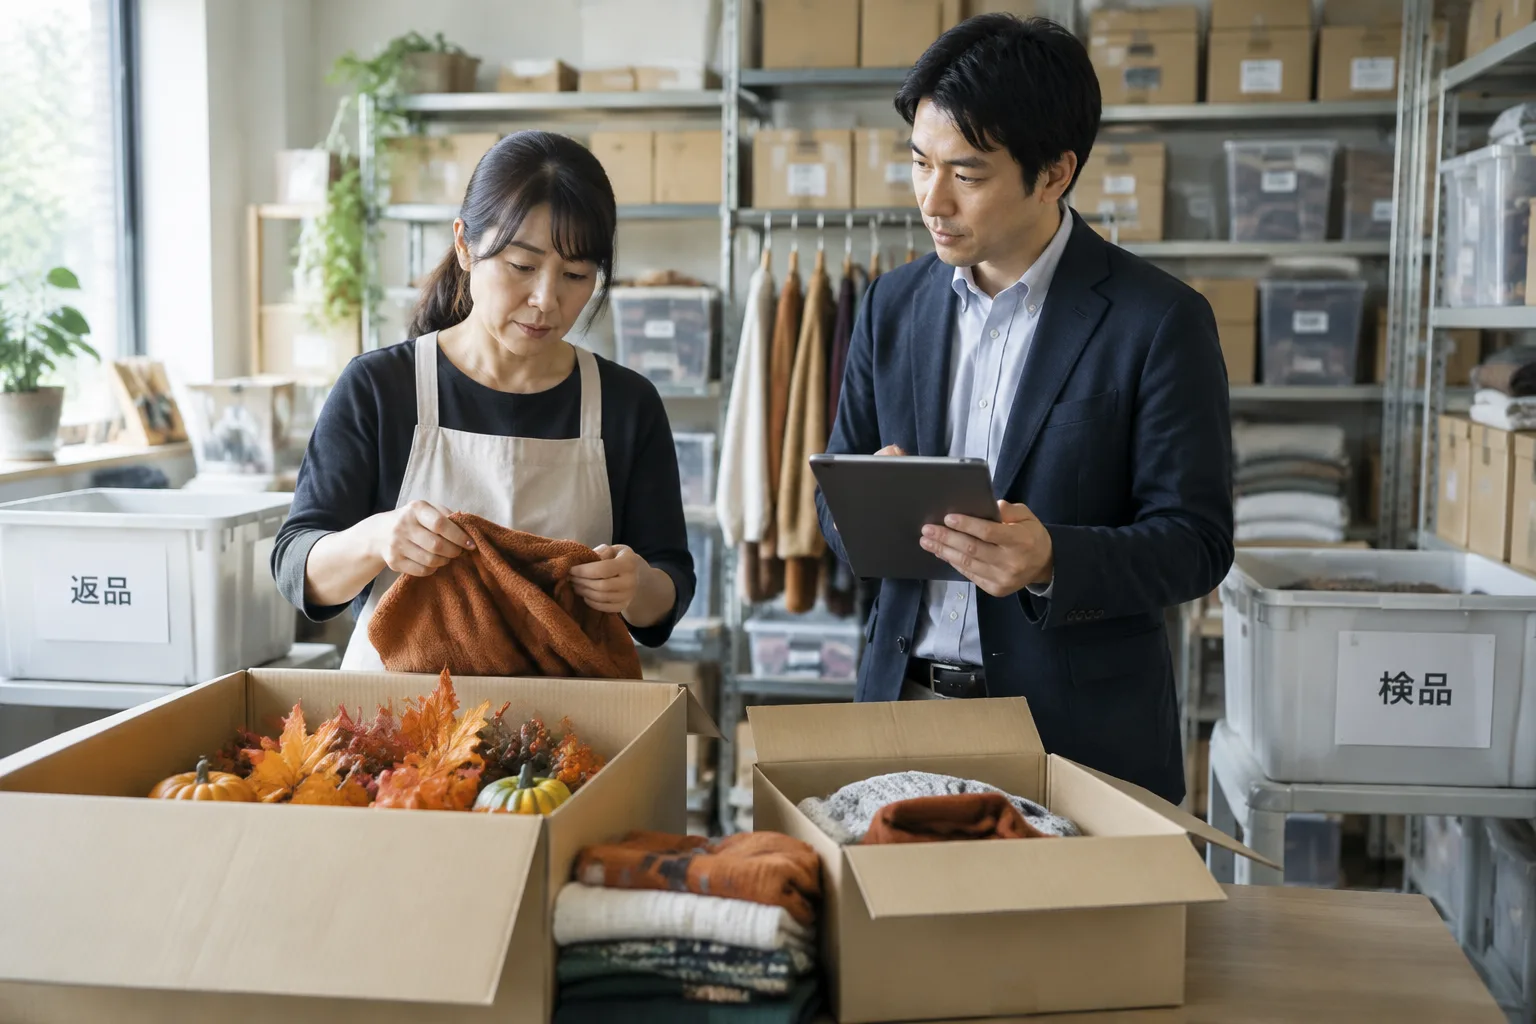
When turning an existing business into a franchise, assessing profitability solely on sales and purchase costs can mean overlooking the burden of unsold stock. Losses from markdowns, returns and disposal that were previously absorbed internally at company-owned outlets must now be allocated between the franchisor and independent franchisees. To build a sustainable franchise network, decide how leftover stock will be handled before recruiting franchisees.
1. Separate the reasons for unsold stock from responsibility for the costs
Start with a table of the situations in which stock may remain unsold, rather than a blanket ‘no returns’ clause. Making either the franchisee or the franchisor bear every loss without examining the cause does nothing to improve ordering or product planning.
At a minimum, consider the following situations separately:
- Demand forecasts prove inaccurate during normal trading
- New or promotional products introduced at the franchisor’s request remain unsold
- Goods arrive damaged, in the wrong quantities or with quality defects
- There are problems with the franchisee’s storage practices or temperature control
- Products can no longer be sold because the franchisor has replaced or discontinued them
For each situation, record who owns the goods, who decides whether they may be sold, who arranges collection or disposal, and who pays. Include not only the cost of the goods but also return freight, inspection and disposal costs. Even if a supplier accepts returns from the franchisor, the same conditions do not necessarily apply to returns from franchisees to the franchisor.
The key issue is the relationship between control over quantities and responsibility for losses. Where the franchisor specifies quantities, consider both how much scope franchisees have to adjust them and the conditions for support from the franchisor. Rather than simply splitting losses equally, base the allocation on who could have prevented them.
2. Measure profitability after waste losses at pilot outlets
Even if company-owned outlets’ accounts capture waste losses, this alone does not reproduce the conditions under which franchisees will operate. If head office staff arrange transfers between outlets, or the founder decides to take back leftover goods, those interventions also need to be recorded.
At pilot outlets, reconcile purchase quantities, sales quantities, markdown amounts, returns, disposals and remaining stock for each product. Test not only normal trading periods but also the end of seasonal ranges and product changeovers. Even for products described as returnable, check that the entire process works in practice, from application and approval through to refund.
When assessing profitability, do more than subtract purchase costs from sales. Include the costs and staff time involved in waste handling, return shipping and disposal. However, avoid double-counting if the purchase cost of discarded goods is already included in the purchase-cost figure. Agree consistent definitions with your accounting team.
The aim is not to make the waste rate look low. It is to be able to explain when stock is left over and which measures reduce losses. If an outlet is only profitable because the franchisor makes exceptional arrangements to take back stock, review the product mix or supply terms before recruiting franchisees.
3. Set return conditions and disposal procedures separately
Returns concern the financial settlement of a transaction; disposal is the operational process of removing goods from sale and discarding them. Combining the two into a single approval process risks leaving unsuitable goods in an outlet while a refund decision is pending.
Return conditions should specify eligible products, application deadlines, condition requirements such as unopened packaging, supporting evidence, the return address, responsibility for shipping costs and the method of settlement. Distinguish the deadline for requesting a return from the deadline for sending the goods back. It is also important not to treat defective goods in the same way as unsold goods that are otherwise satisfactory.
Disposal procedures should cover stopping sales, segregating goods from the sales area, checking quantities, keeping records such as photographs, the disposal method and confirmation of completion. Where there are safety concerns, staff should be able to stop sales and segregate goods before responsibility for the costs has been settled. You must also check the safety and waste legislation applicable to food and other relevant product categories.
For example, if the franchisor sets a final sales date for a seasonal product, state in advance whether stock left over on that date can be returned and what deadlines apply. Even where returns are not permitted, make clear whether stock can be transferred between outlets or sold beyond that date, so franchisees know what options are available.
4. Align contracts and recruitment disclosures with Japanese rules
Japan has no single law comprehensively governing franchising alone. However, certain arrangements fall under the Act on the Promotion of Small and Medium-sized Retail Business. The Civil Code governs contractual relationships, while legislation including the Antimonopoly Act is relevant to dealings between franchisors and franchisees.
Article 11 of the Act on the Promotion of Small and Medium-sized Retail Business requires franchisors operating a ‘specified chain business’ to provide written disclosures and explanations before a contract is concluded. Broadly, this covers arrangements under which a business continuously sells goods, or arranges their sale, primarily to small and medium-sized retailers under standard-form contracts, provides management guidance, and stipulates the use of specified branding and payment of a joining fee. Do not determine whether the Act applies merely from labels such as ‘retail’ or ‘food service’.
The Japan Fair Trade Commission’s guidelines on franchise systems under the Antimonopoly Act are relevant regardless of the type of business. If a franchisor’s conduct goes beyond what is necessary to operate the system properly and unfairly disadvantages franchisees, it may raise issues such as abuse of a superior bargaining position. Including a provision in the contract does not, by itself, justify imposing excessive stock or losses on franchisees.
Stock-cost responsibilities and return conditions should therefore be consistent across the contract and the materials used when recruiting franchisees. Avoid a situation in which the written explanation says ‘no returns in principle’ while a representative verbally promises to buy stock back. A practical approach is to define the allocation of costs clearly in the contract and set out day-to-day application and record-keeping procedures in the operating manual.
5. Record exceptions and feed the findings back into product planning
Demand forecasting immediately after opening and sales of new products involve uncertainty. Where exceptional returns or costs borne by the franchisor are approved, record who authorised the decision, the evidence considered, the quantities covered and the financial settlement. Avoid relying on verbal promises to individual outlets; comparable circumstances should be assessed against consistent criteria.
Franchisors should examine trends by product and cause, not just the value of waste at each outlet. If the same product remains unsold across several outlets, review the range, order quantities, sales period and demand forecasts rather than assuming franchisees have not tried hard enough. Even if return applications are rare, listen to franchisees to establish whether a complicated process is discouraging them from applying.
Practical takeaway: Before recruiting franchisees, prepare a one-page summary for key products covering ‘why stock remains unsold, who has decision-making authority, return conditions and responsibility for costs’. Test it at pilot outlets, then incorporate the findings into contracts and manuals to reduce misunderstandings over unsold stock.