PZZA Profit Rises 7.6% as Pizza Hut Sales Continue to Fall
PZZA’s net profit reached IDR 17.1 billion in the nine months to September 2026, but sales and operating profit fell. Its network stood at 576 outlets.
Published
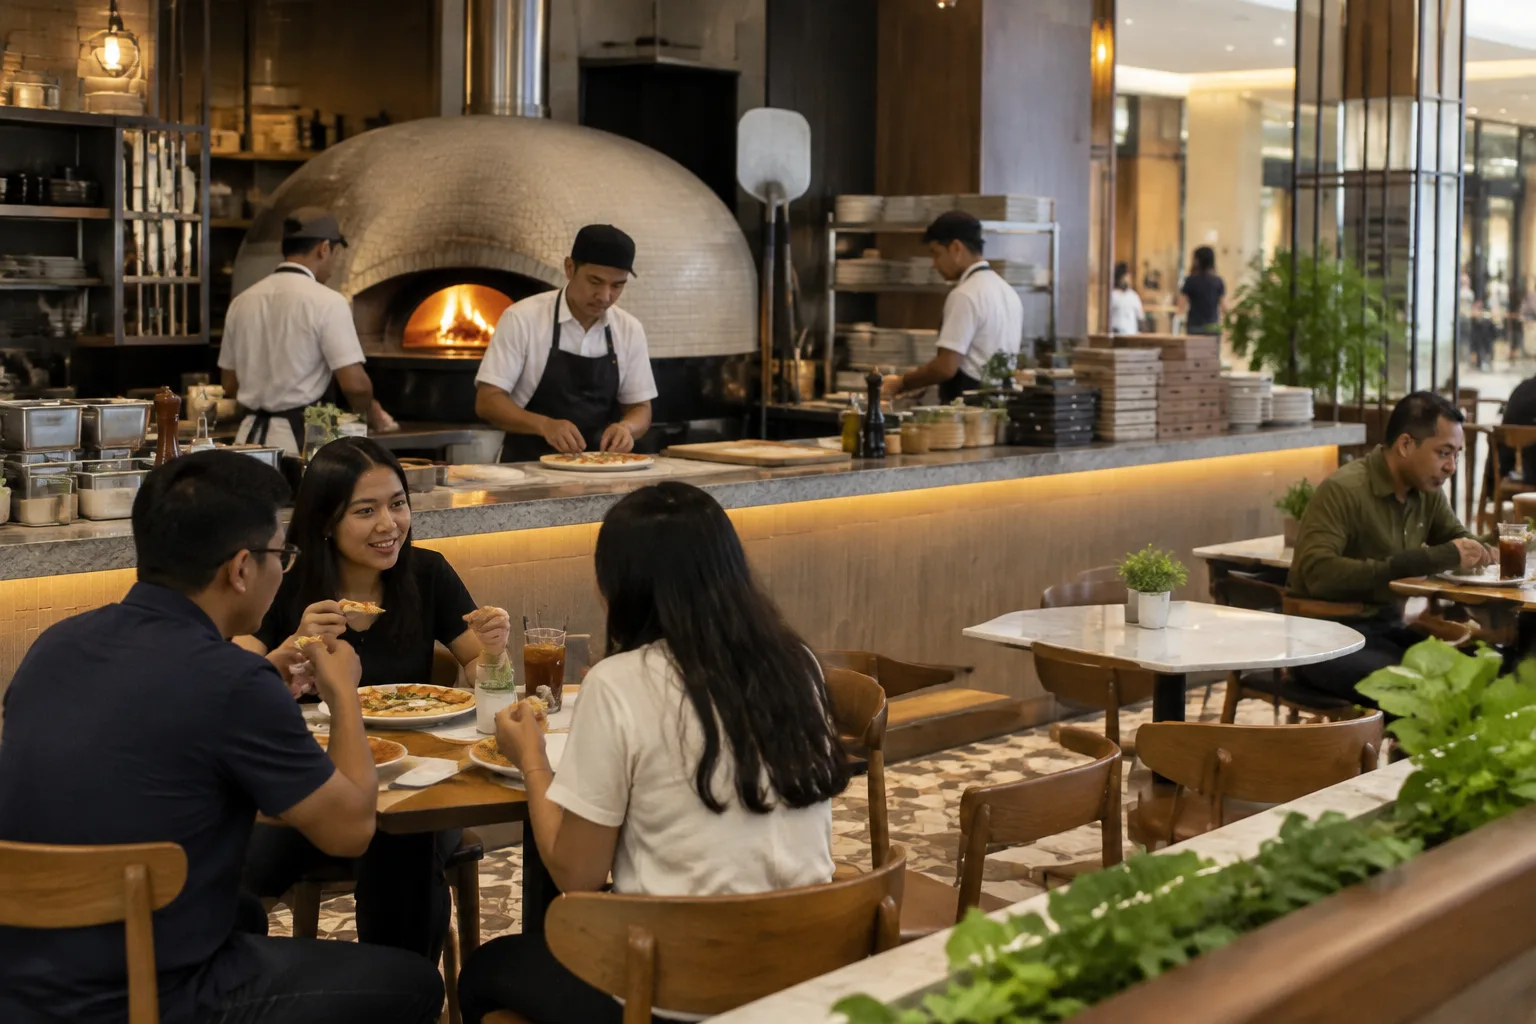
PT Sarimelati Kencana Tbk (PZZA), the franchise holder for Pizza Hut and PHD in Indonesia, reported higher net profit for the first nine months of 2026 despite declining sales and operating profit. These diverging indicators highlight an important point for those assessing restaurant networks in Indonesia’s franchise market: an improved bottom line does not necessarily mean stronger operating performance.
Net profit grows despite falling sales
According to a report by The Signal on 16 November 2026, Sarimelati Kencana submitted its annual public presentation materials covering performance for the first nine months of 2026, accompanied by a letter signed by Corporate Secretary Andromeda Tristanto. The submission followed an announcement on 5 November 2026 of plans to hold the public presentation.
The materials showed net sales of IDR 2,241 billion, down 1.1% from IDR 2,265.6 billion in the same period a year earlier. Revenue for the nine months to September therefore remained below the previous year’s level.
Net profit, however, rose 7.6% to IDR 17.1 billion from IDR 15.9 billion. The net profit margin remained at around 0.8%. This indicates that, although the company’s bottom line improved, the proportion of sales converted into net profit remained relatively small.
These two trends need to be considered together. Net profit growth is a positive development for the bottom line, but falling sales mean the company did not achieve year-on-year revenue growth for the period. The increase in profit should therefore not be taken as evidence that every performance measure has improved.
Gross margin improves, but operating profit weakens
Sarimelati Kencana reported gross profit of IDR 1,587.4 billion, up 0.8%. Its gross profit margin also increased, from 69.5% to 70.8%, despite the slight decline in sales.
That improvement did not carry through to operating profit. Operating profit fell 17.9% to IDR 40.6 billion, compared with IDR 49.4 billion in the first nine months of the previous year. The operating profit margin narrowed from 2.2% to 1.8%.
The report therefore shows three simultaneous developments: higher gross profit, lower operating profit and higher net profit. These represent different levels of financial performance and should not be treated as interchangeable when assessing the company’s position.
For those in the franchise sector, examining these different levels is important when evaluating a business network. Net profit shows the bottom-line result, while operating profit helps assess performance at an operational level. In PZZA’s case, the improvement in the bottom line was not matched by operating profit. Nor is this data sufficient to conclude that every outlet is in the same financial position.
Network contracts to 576 outlets
Alongside these changes in financial performance, PZZA’s Pizza Hut network stood at 576 outlets across more than 120 cities at the end of September 2026. This was seven fewer than the 583 outlets recorded a year earlier.
That figure represents the net year-on-year change in the network. The difference of seven outlets does not, by itself, reveal the total number of openings or closures during the period.
By region, the Jakarta, Java and Bali grouping fell from 417 to 414 outlets. Sumatra declined from 77 to 76, Sulawesi from 35 to 34, and Kalimantan from 39 to 37. Eastern Indonesia remained unchanged at 15 outlets.
Jakarta, Java and Bali remained the network’s main concentration, accounting for 414 of its 576 outlets. Sumatra followed with 76, then Kalimantan with 37, Sulawesi with 34 and Eastern Indonesia with 15. This distribution shows that most outlets remained in the first regional grouping, despite its year-on-year decline in outlet numbers.
Assessing profitability beyond outlet numbers
Performance for the first nine months of 2026 presents a mixed picture. PZZA generated higher net profit with a smaller network, but sales and operating profit remained below the comparable period. The improvement in gross margin was also not matched by a higher operating margin.
For franchise sector participants, the figures are a reminder to assess network size and profitability separately before examining how they relate. Outlet numbers indicate a business’s reach, but do not automatically reflect its profitability. Equally, an increase in net profit does not explain every development in sales or operations.
Practical takeaway: when evaluating a franchise network’s performance, review sales, operating profit, net profit and changes in outlet numbers over comparable periods. Do not base a decision on a single figure.