Buying a Franchise: Agree Your Obligations During Emergency Closures
Check emergency closure provisions before buying a franchise: payments, notification, evidence of the incident and conditions for reopening.
Published
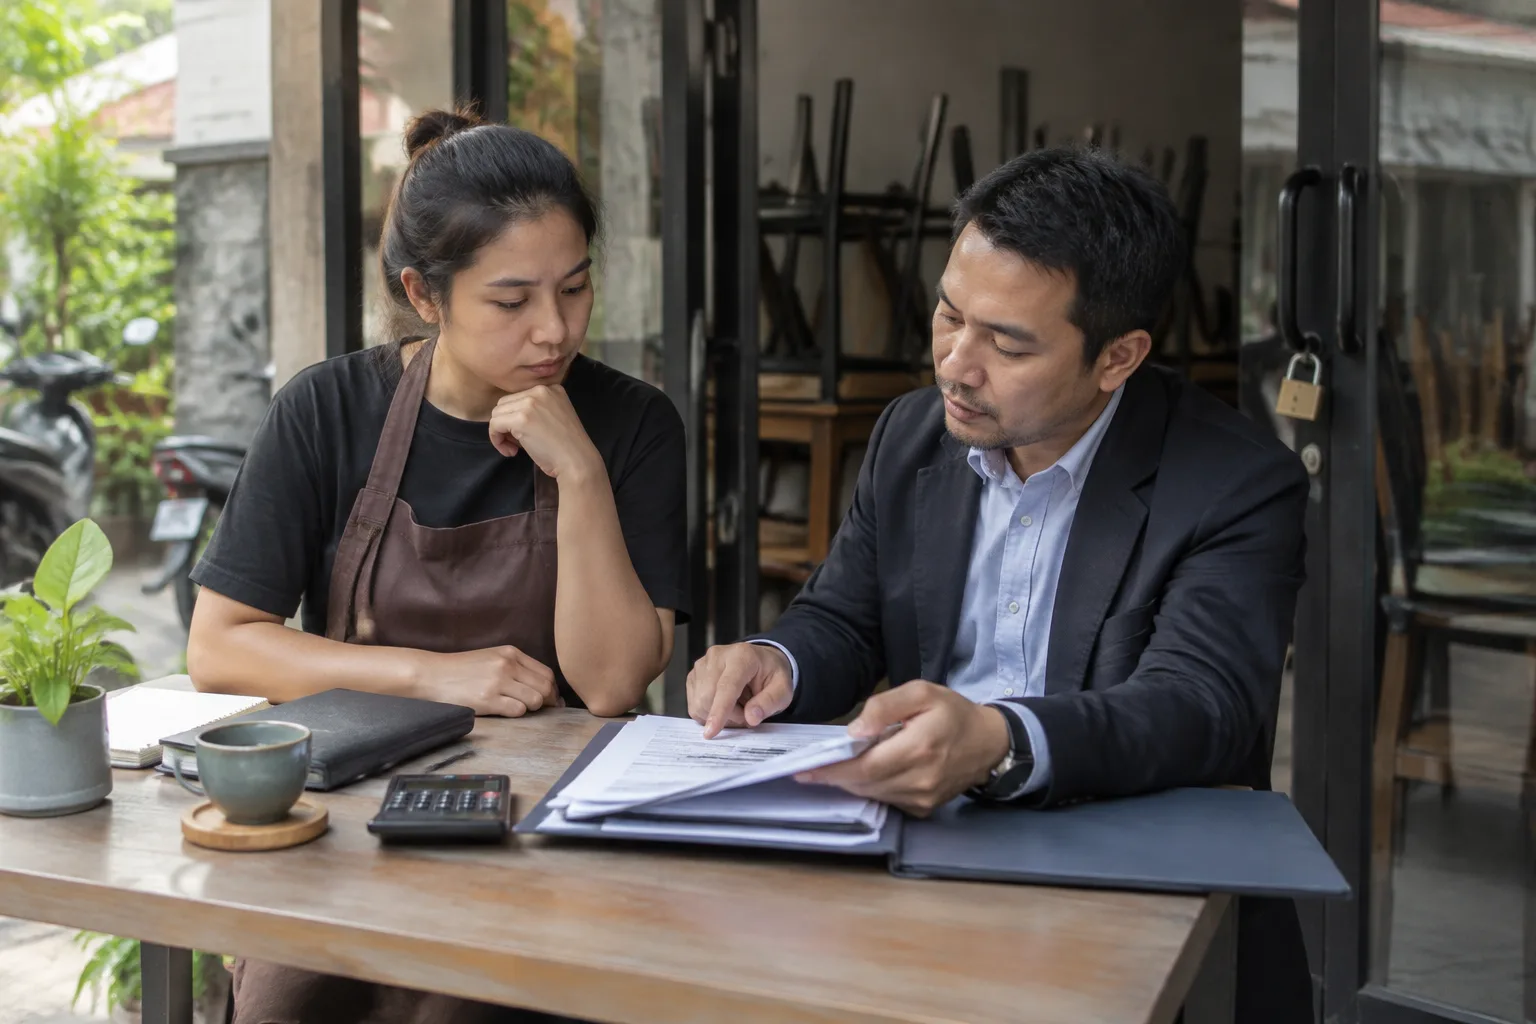
Flooding, fire or restrictions on access to a building can force an outlet to stop trading even when its owner is ready to work. However, a halt in sales does not automatically suspend bills or contractual obligations. Before buying a franchise, make sure the agreement sets out what both parties must do if the outlet has to close in an emergency. Clear allocation of risk helps protect franchisees while maintaining trust in the brand.
1. Distinguish force majeure from ordinary business risks
Force majeure does not simply mean circumstances that make a business difficult to run or less profitable. Falling sales, staff shortages and a lack of working capital should not automatically be treated as grounds for disregarding a contract.
Under Indonesian law, Articles 1244 and 1245 of the Indonesian Civil Code provide an important basis for assessing relief from liability for costs, damages and interest arising from a failure to fulfil an obligation because of certain circumstances beyond the debtor’s responsibility. Their application depends on the facts, the causal link and the terms of the agreement. These provisions do not automatically cancel all payment obligations.
Ask for the draft contract to distinguish between three situations:
- The outlet cannot be accessed, for example because the building has been officially closed following a disaster.
- The outlet may operate on a limited basis, for example for order collection only.
- The outlet closes because of the operator’s negligence, for example following a breach that affects its operating licence.
These distinctions matter because the contractual consequences may differ. In the case of a fire, for instance, its cause and impact must be assessed; the type of incident alone is not enough to establish relief from liability.
2. Check the clauses before signing the agreement
Franchising in Indonesia is specifically governed by Government Regulation No. 35 of 2024 on Franchising, which replaced Government Regulation No. 42 of 2007. The regulation requires prospective franchisees to receive a Franchise Offering Prospectus at least 14 calendar days before signing the Franchise Agreement.
Use this period to request the draft agreement and review how the risks of an emergency closure are allocated. Do not assume that the requirement to provide a prospectus means the contract automatically includes all the protections you need.
Seek written answers to the following questions:
- Which events can trigger a temporary closure without breaching the obligation to keep the outlet open?
- Is a decision by the government or building management required, or is other evidence acceptable?
- Who has authority to approve limited operations and reopening?
- What happens if an incident affects only one outlet rather than the entire network?
Avoid wording that leaves every decision to “the franchisor’s policy” without specifying criteria or response deadlines. Equally, do not seek blanket relief that disregards obligations to maintain safety, secure stock and protect customers.
3. Identify which bills will continue
List the obligations that apply while the outlet is closed, then ask for each to be explained. Separate payments calculated on transactions from fixed payments. A lack of sales may reduce a bill, but it will not necessarily remove an agreed minimum payment.
Use a simple working table with columns for type of obligation, payee, treatment during closure and payment deadline. Include payments to the franchisor as well as relevant bills from other parties.
For each payment, distinguish clearly between:
- Waiver: a specified obligation is not charged for the agreed period.
- Reduction: only part of the amount is payable.
- Deferral: the obligation remains, but the due date is moved.
Deferral is not a permanent saving. If all outstanding amounts become payable at once when the outlet reopens, cash requirements may surge before sales have recovered.
Also check whether interest, penalties or a contractual default can still arise during an approved deferral. An agreement with the franchisor does not automatically bind the landlord, bank or suppliers. Contracts with each party need to be reviewed separately.
4. Agree emergency procedures and closure limits
Contractual protection is difficult to rely on if its procedures cannot be followed in practice. Make sure notices can be sent through realistic channels, including when the office or outlet is inaccessible. Specify who should receive notice, the deadline and an alternative route if the main contact does not respond.
Prepare a list of evidence that may be required: notices from building management, records of damage, decisions by the authorities and a record of the date trading stopped. Also set out obligations to provide updates and take reasonable steps to limit losses, where it is safe to do so.
Negotiate a mechanism for dealing with a prolonged closure. Options may include a joint review, approved temporary operations or termination under an agreed procedure. Do not assume the franchise term will automatically be extended by the length of the closure; any extension must be expressly provided for.
Before signing, test the clauses against one scenario: the outlet is inaccessible and sales have stopped, but bills keep arriving. Ask a legal adviser to assess whether the contract provides consistent answers.
Practical takeaway: buy a franchise only once you understand who must do what, which payments will continue and how the outlet can reopen when the emergency ends.
Sources
- Panduan Beli Waralaba, Tata Cara Hingga Akad Fikih Biar ...
- Menimbang
- Waralaba: Syarat dan Hukum di Indonesia | PDF
- Contoh Perjanjian Waralaba yang Aman & Anti Penipuan!
- Jurnal Lex Suprema
- PERATURAN PEMERINTAH REPUBLIK INDONESIA
- PERJANJIAN WARALABA DAN PERSAINGAN USAHA
- BERITA NEGARA REPUBLIK INDONESIA - peraturan.go.id