How Chinese Businesses Can Manage Near-Expiry Stock and Wastage Before Franchising
Steady sales do not necessarily mean stock management is mature. Before franchising, businesses should test near-expiry alerts, stock transfers and rules for allocating losses in company-owned stores, rather than passing unreasonable stocking pressures on to franchisees.
Published
When preparing to develop an existing business into a franchise network, companies can easily focus on sales while overlooking goods nearing expiry on shelves and in storerooms. For shops selling food, cosmetics and other products with a limited shelf life, excess stock can affect not only profits but also product quality and consumer rights. Head office should first demonstrate that an ordinary store manager can follow standard rules to identify near-expiry stock, deal with it promptly and record losses accurately.
1. Establish minimum quality requirements, then define near-expiry thresholds
China has specific regulations governing commercial franchising. Article 7 of the Regulations on the Administration of Commercial Franchising requires franchisors to have a mature business model. Article 14 requires them to provide an operations manual and ongoing guidance, support and training as agreed. Article 15 requires the quality and standards of products or services to comply with laws, administrative regulations and relevant national requirements. Stock management is a practical part of meeting these obligations, but the regulations do not set a single near-expiry period for all products.
Businesses should establish categories based on product characteristics, labelling requirements, storage conditions and applicable rules. They should not apply a blanket policy of dealing with every product one month before expiry. Where materials have a shorter usable life once opened than their original packaged shelf life, the opening date and deadline for use must also be recorded separately.
Consider setting three internal management thresholds for each product category:
- Alert threshold: Check how many days of sales the stock will cover, and reduce or suspend replenishment.
- Action threshold: Assess whether compliant promotions, stock transfers or returns under agreed terms are feasible.
- Stop-sale threshold: Segregate the goods, stop selling or using them, and process a stock write-off.
Internal thresholds must stay within legal and labelling requirements. Even if a product has not yet expired, damaged packaging or unsuitable storage conditions mean the date alone cannot establish whether it is still fit for sale.
2. Test replenishment and stock rotation rules in company-owned stores
Start with a trial in company-owned stores operating under normal conditions, rather than selecting only those with the strongest sales and fastest stock turnover. Testing should cover the whole process: receiving goods, shelving, opening, replenishment, stocktaking and write-offs. Managers should be able to carry out the work by following the rules, rather than waiting for the founder to assess each batch.
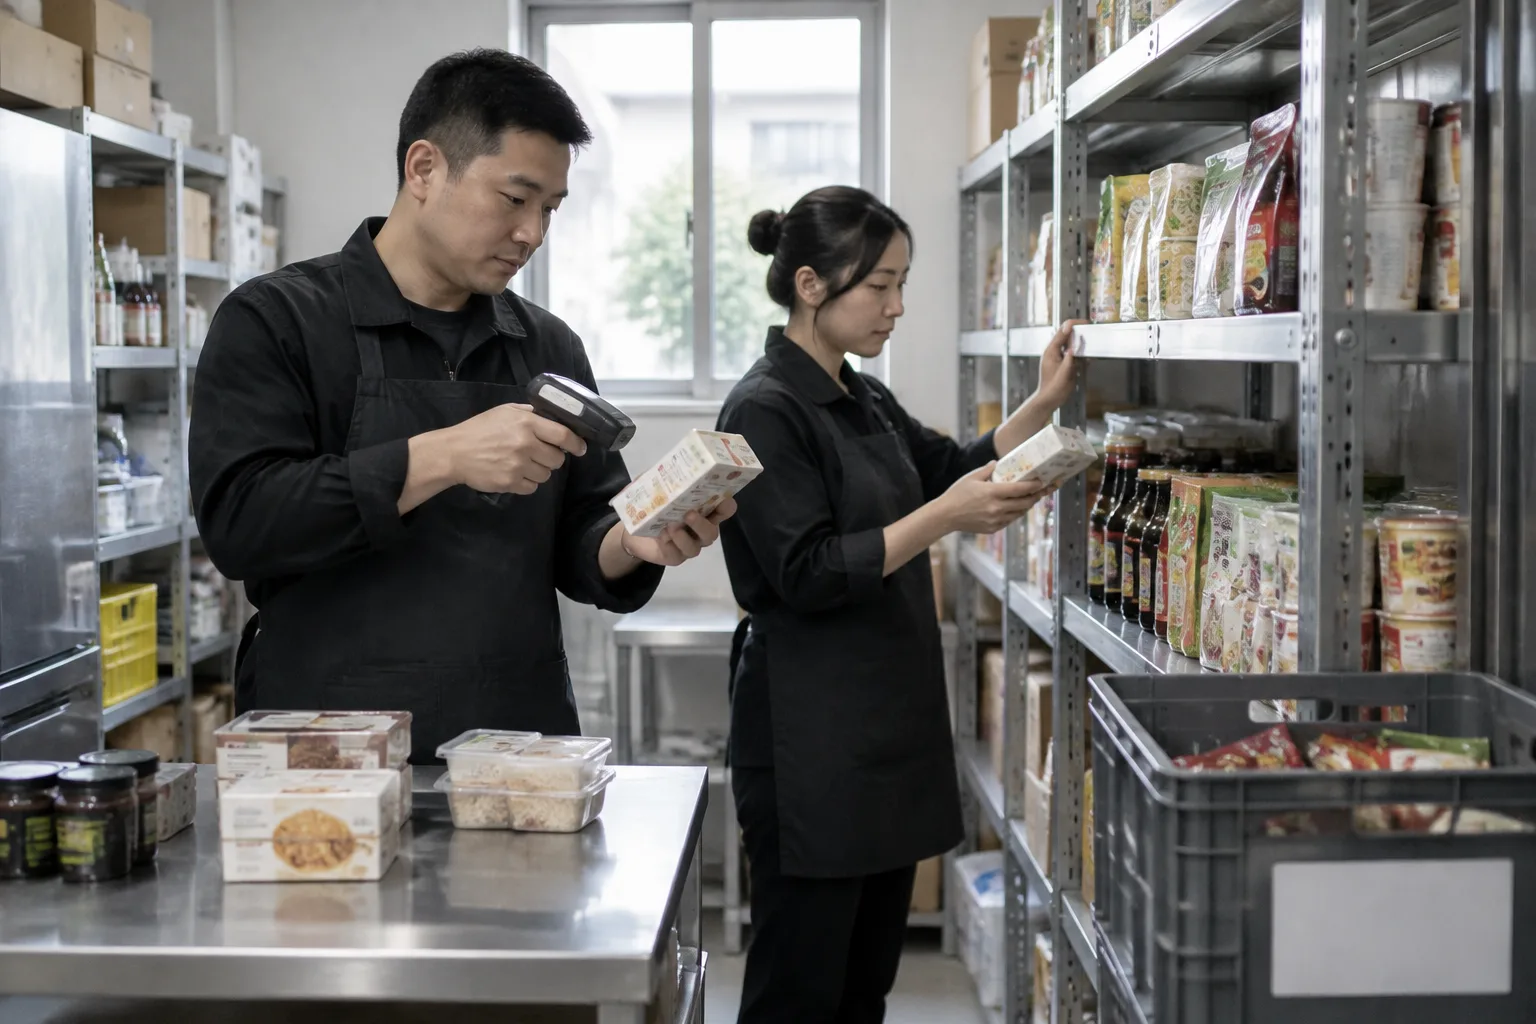
When goods arrive, checks should cover at least the product, quantity, batch, expiry date and storage condition. Deliveries with insufficient remaining shelf life for normal sales should be handled according to pre-agreed acceptance criteria. They should not simply be accepted and left for stores to sell through.
Stock issuing and display can follow a ‘first expiry, first out’ approach, while preserving batch traceability. Where the same product has several batches with different expiry dates, recording only the total quantity is not enough. Otherwise, the system may show stock available without staff being able to identify which batch needs to be used first.
The trial should monitor both stockouts and write-offs, so that very low stock levels do not produce misleadingly good wastage figures. Record losses separately according to whether they result from over-ordering, insufficient remaining shelf life on arrival, inaccurate sales forecasts, poor storage or operational errors. Then adjust ordering frequency, minimum order quantities and safety stock. The trial period should cover a complete replenishment and near-expiry stock management cycle, not just an opening promotion.
3. Clearly document decision-making authority and responsibility for costs
Once a business is franchised, near-expiry stock often involves head office, suppliers and franchisees. Before recruiting franchisees, the business should clarify who can authorise price reductions, who can approve transfers, which goods can be returned, who pays transport costs and what evidence is required for a write-off.
Consider drawing up a ‘cause–responsibility–evidence’ table. For example, if a delivery fails to meet agreed acceptance criteria, retain the goods receipt records and address the issue under the supply contract. If a store has failed to follow storage requirements, check its operational records. If excess stock results from stocking requirements for a head-office-led promotion, handle it under the terms agreed in advance, rather than unilaterally shifting the cost afterwards. Responsibility should be determined by the facts and the contract, not by a blanket rule that franchisees are responsible for everything once goods enter the store.
Article 11 of the Regulations on the Administration of Commercial Franchising requires written contracts to include key provisions such as quality standards and assurance measures, relevant fees and liability for breach of contract. Important terms allocating stock-related risks should be consistent with the franchise agreement and purchasing documents, rather than appearing only in training slides.
The regulations also require relevant information to be disclosed in writing, and the contract text to be provided, at least 30 days before the contract is signed. Matters such as minimum order quantities, supply terms and charges associated with handling stock should be included in the applicable disclosures. This allows prospective franchisees to assess how much capital will be tied up, rather than discovering the true burden after signing.
4. Use straightforward records to support continuous improvement
The operations manual should provide tools that staff can use directly: near-expiry checklists, stock transfer request forms and write-off records. Records should include at least the product batch, quantity, date, reason, action taken and approving person, with photographs and evidence of destruction where necessary. Retention periods should be determined according to applicable legal and business requirements.
Systems must also support implementation. Whether using software or paper records, goods withdrawn from sale should no longer be available for routine issue, written-off stock should no longer count towards saleable quantities, and original batch and expiry details must be preserved after transfers. Before transferring goods between stores, confirm that transport and receiving conditions meet the products’ requirements.
Head office reviews should do more than publish wastage rankings. They should distinguish between ordering, supply and implementation problems, so that stores are not encouraged to conceal write-offs to protect their performance ratings. For recurring losses, assign responsibility for changing ordering parameters, pack sizes or operating procedures, and check the results afterwards.
Practical takeaway: Complete the entire process in company-owned stores, from the first near-expiry alert to closing the write-off record, before offering franchises. A mature stock management system is not about achieving ‘zero write-offs’. It is about making risks visible early, ensuring actions are properly supported and agreeing in advance who bears the costs.