Buying a Franchise in Saudi Arabia: How to Calculate Your Cash Reserve
Opening costs are only part of your investment. Learn how to calculate the cash reserve needed to bridge the gap between receipts and payments before buying a franchise in Saudi Arabia.
Published
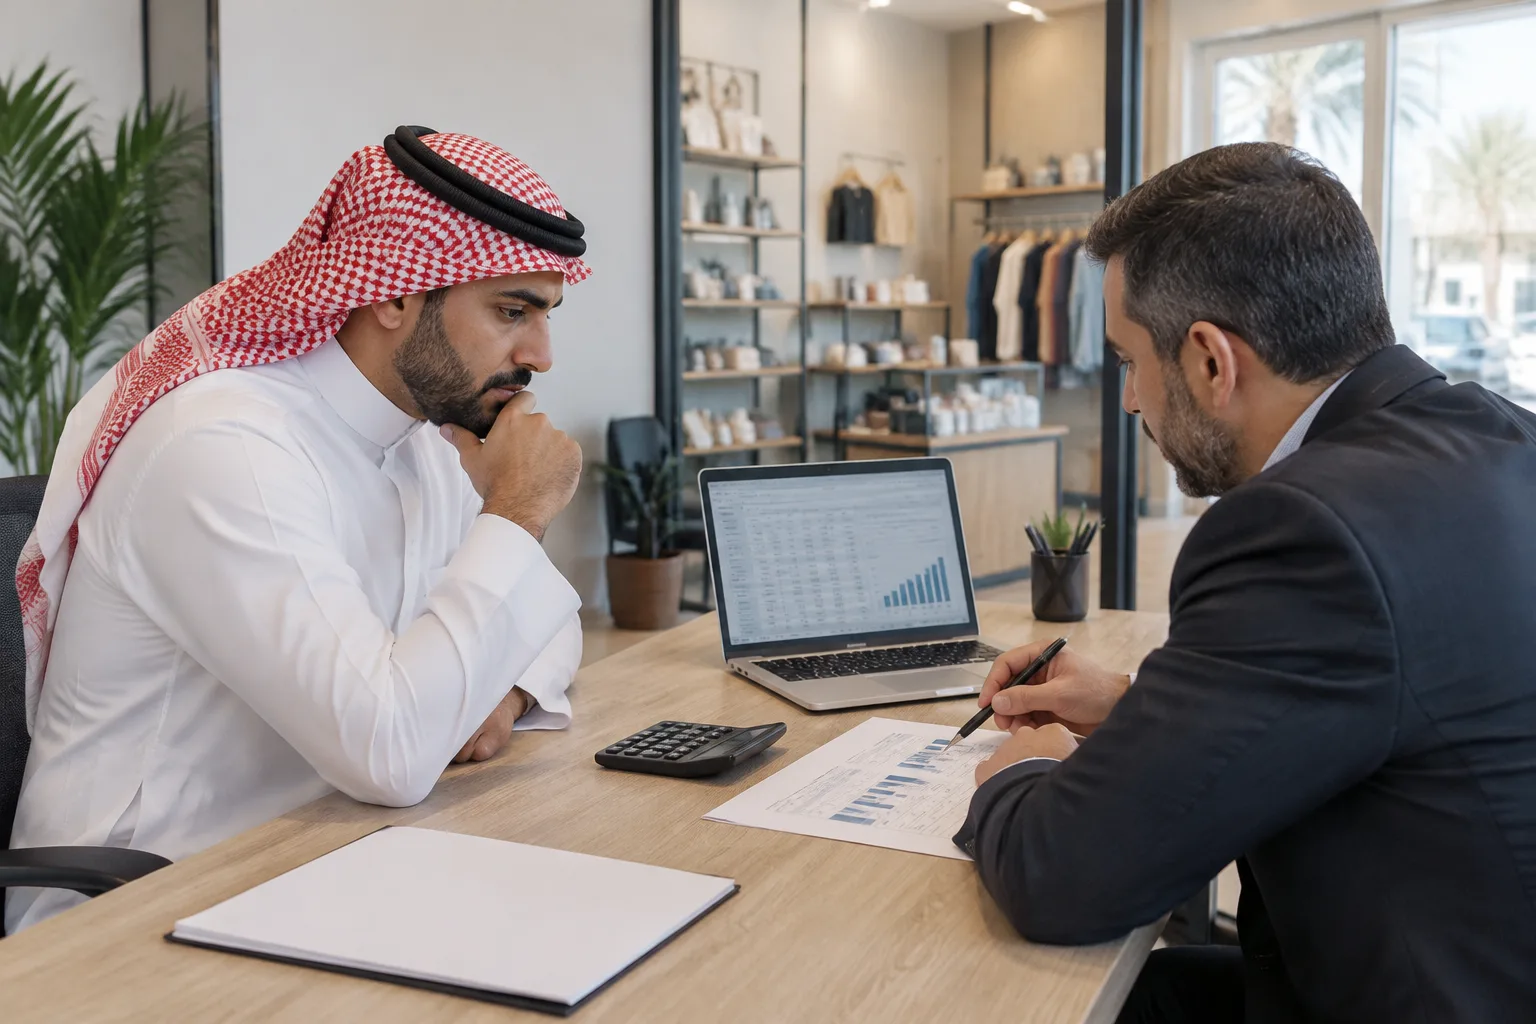
You may be able to pay the franchise fee and fit out your premises, but can you keep the business running if revenue is delayed? In franchising, a fully funded opening budget is not enough to protect a business from cash shortages. Before buying a franchise in Saudi Arabia, calculate your cash reserve as part of the purchase decision, rather than treating it as whatever is left after the fit-out. The aim here is not to forecast profits, but to understand when money goes out and when it actually comes in.
Separate opening costs from the cash needed to keep trading
Start with three separate lists: set-up payments, operating payments, and funds that are restricted or unavailable for day-to-day use. The first includes initial franchise fees, fit-out, equipment and pre-opening expenses. The second covers salaries, rent, purchases, utilities and services, loan repayments and amounts due to the franchisor. The third may include refundable deposits or funds held under contractual arrangements.
This distinction matters because money refundable in the future cannot pay wages due today, and equipment you own is not readily available cash in the bank. Likewise, do not treat opening stock as a cash reserve: you may need to buy another batch before receiving full payment for the first.
Ask the franchisor for a breakdown of what the investment estimate includes and excludes. Does it cover salaries during the preparation period? Does it allow for rent during the fit-out, staff recruitment or overseas recruitment costs, and technology subscriptions? Record every unresolved item rather than assuming it falls under the heading of ‘project cost’.
Then separate your personal needs from the outlet’s finances. If you rely on the business to cover your living costs, clearly include your expected drawings in the plan or set aside a separate personal reserve. Leaving this need out makes the cash position look healthier than it will be.
Build a receipts and payments schedule, not just a list of expenses
Create a cash flow forecast that starts before opening and continues until it is clear whether the outlet can fund its commitments. Use weekly periods where payment dates fall close together, then monthly periods for longer-term planning. For each period, record the opening balance, expected cash actually received, payments due and closing balance.
Do not assume that every sale immediately becomes cash coming in. Check settlement times for electronic payments, transfers from ordering platforms where applicable, and payment terms for business customers. Similarly, enter stock purchases according to when the supplier must be paid, not when the products are sold.
Pay particular attention to these items:
- Rent: is it payable in advance or in instalments?
- Salaries: when do payments start relative to the arrival of your first customer?
- Stock: are advance payments or minimum order quantities required?
- Finance: when do repayments begin, and what conditions apply to the release of funds?
- Payments to the franchisor: do they fall due before you receive the proceeds of the related sales?
- Taxes: how will payment dates and potential refunds affect cash, given the business’s tax position?
Ask an accountant to ensure VAT is handled correctly. Do not assume that VAT collected is permanently available to spend, or that an expected refund will arrive immediately. Include the principal element of loan repayments in cash outflows, even though it is treated differently from expenses in the profit and loss account.
Base your reserve on the largest cash shortfall
Calculate cumulative cash flow before adding an operating reserve, and identify the lowest balance it reaches. The shortfall at that point forms the basis of the reserve required. Then add a safety margin proportionate to the risks you can identify. Avoid counting the same amount twice if it is already included in the set-up budget.
Do not rely on a single scenario. Test the effects of a delayed opening while rent and salaries continue, slower receipts, and the need to replenish stock earlier than expected. Also test what happens if a large rent payment coincides with a loan repayment and amounts due to the franchisor. The problem may lie in several payments falling due together, rather than simply in the overall cost being high.
For every assumption, record its basis: a quotation, a repayment schedule, a contractual term or an estimate that needs checking. This prevents reassuring forecasts from becoming accepted facts in the budget and highlights where you need more information before deciding.
There is no single reserve period that suits every brand. Covering a fixed number of months’ expenses may be a starting point, but it is no substitute for calculating the actual cash shortfall. Nor should you count hoped-for finance or verbal promises of support from the franchisor as available funds. Distinguish between cash already held, approved finance available to draw down, and uncertain sources of funding.
Use the calculation before committing to buy
Franchise relationships in Saudi Arabia are governed by the Commercial Franchise Law, issued under Royal Decree No. (M/22), and its Implementing Regulations. The law requires the franchisor to provide the disclosure document at least fourteen days before the franchise agreement is signed or any franchise-related payment is made, whichever occurs first. Use this period to reconcile the stated costs with your cash flow forecast. Do not treat the end of that period as evidence that your capital is sufficient.
Request written clarification of any unresolved payment dates, and discuss whether large payments can be spread out before signing. Any deferral or payment concession on which your plan depends must be documented. It is a negotiated arrangement, not an automatic entitlement arising from a need for cash.
Base your decision on your ability to fund both the fit-out and the operating cash shortfall. If opening would exhaust all your funds, reconsider the size of the outlet or the timing of the purchase rather than relying on immediate sales.
Practical takeaway: Do not just ask: how much does it cost to open the outlet? Ask: what is the lowest forecast cash balance, when will it occur, and what confirmed source of funds will cover it?
Sources
- الدليل الكامل للامتياز التجاري
- دليل الامتياز التجاري في السعودية 2026: الشروط، الخطوات، والتكاليف - تنفيذ الأعمال للخدمات الحكومية
- كيف آخذ فرنشايز - دليل شامل
- الامتياز التجاري والفرنشايز في السعودية - عاهد
- دليل عقود الامتياز التجاري (الفرنشايز) في السعودية 2026
- أنواع الامتياز التجاري: دليلك الشامل لاختيار نموذج الفرنشايز ...
- كتاب عن الاستثمار الآمن بنظام الفرنشايز - Franchising.sa
- ما هو الامتياز التجاري؟ دليل الفرنشايز في السعودية