PIVALDI offers a 70-seat urban restaurant franchise
PIVALDI is expanding its PIVALDI CITY franchise offering, based on a 70-seat restaurant in Khimki. The stated minimum investment is RUB 25 million.
Published
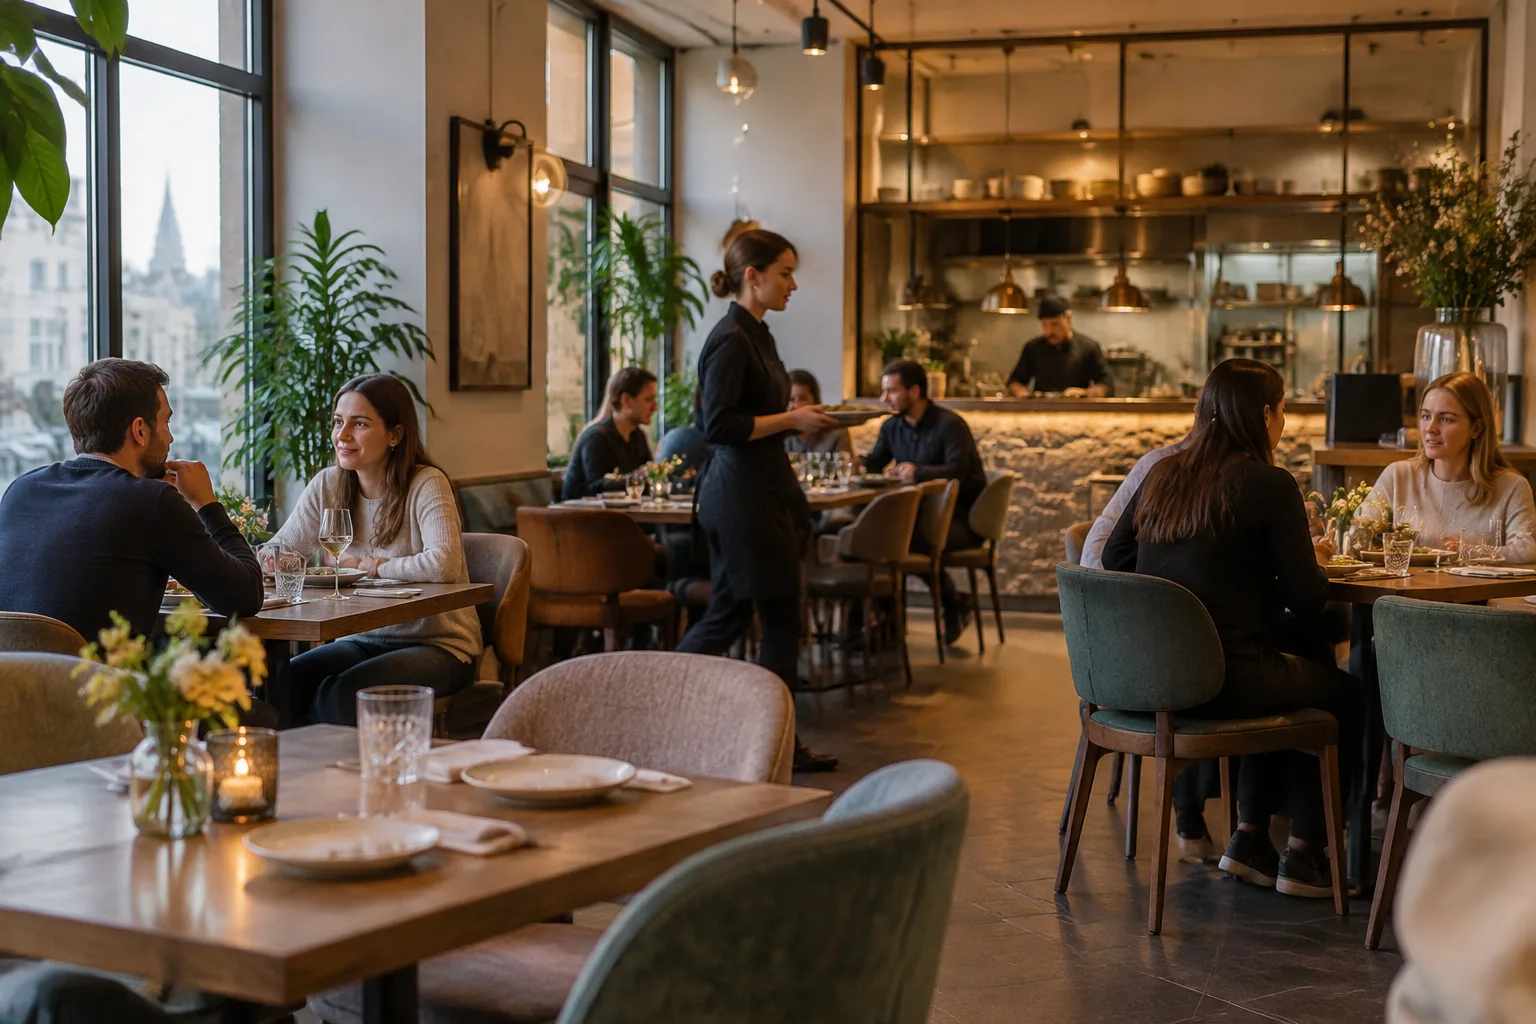
Restaurant chain PIVALDI is offering prospective franchisees PIVALDI CITY, a smaller restaurant format represented by a 70-seat venue in Khimki, near Moscow. In an interview published by Forbes on 30 September 2026, Artur Azaryan outlined the terms of the offer and plans for expansion in Moscow. For prospective franchisees, the key point is that the offer covers the compact format, not the chain’s large restaurants.
From large restaurants to PIVALDI CITY
According to the article, PIVALDI has been opening restaurants in Moscow and the surrounding area since 2018. It currently operates four large restaurants with a combined capacity of more than 4,000 seats. A separate 70-seat PIVALDI CITY restaurant operates in Khimki, and it is this format that is available as a franchise.
The difference in scale matters when assessing the offer. Information about the large restaurants illustrates the chain’s experience, but does not in itself show how a smaller franchised venue would perform. The PIVALDI CITY restaurant should be the starting point for any franchise assessment, with figures for the larger sites considered separately.
The interview’s headline highlights Azaryan’s goal of opening a restaurant in every district of Moscow. This is a statement of intent, not confirmation of completed openings or signed agreements. The information provided does not establish how many franchised venues are planned, where they would be located or when they would open. The Moscow plans are therefore best understood as the chain’s ambition rather than a confirmed expansion timetable.
What terms are offered to franchisees?
The article sets out the main financial terms of the PIVALDI CITY franchise:
- initial franchise fee: RUB 5 million;
- minimum investment: RUB 25 million;
- royalty: 8% of revenue;
- estimated payback period: 18 months.
These figures provide an initial framework for discussions, but are no substitute for a detailed cost breakdown. The information supplied does not specify whether the initial franchise fee is included in the minimum investment. It would therefore be misleading to add the two amounts together and present the result as the definitive start-up cost. Prospective franchisees should clarify this before comparing the offer with other options.
The investment budget also needs clarification: which costs are covered by the stated minimum, and which must the operator budget for separately? These are due diligence questions, not confirmed additional charges imposed by PIVALDI.
The source describes the 18-month payback period as an estimate. It should not be treated as a guaranteed outcome for every location. Assessing an individual project will require an understanding of the revenue, cost and capacity utilisation assumptions behind the calculation, followed by a comparison with the chosen premises and lease terms.
What is known about the Khimki restaurant’s financial performance?
Azaryan reported that, over the previous four months, the Khimki restaurant’s profit margin was 24% before royalties and 16% after payment. This is the most specific financial performance figure provided for the smaller format.
However, it is a result reported by a representative of the chain for a single restaurant over a limited period. The extract does not explain how the margin was calculated or provide a detailed cost breakdown. Without that context, the figure should not automatically be carried over into a prospective franchisee’s financial model.
The interview also states that restaurant revenues reach up to RUB 100 million a month. The information provided gives no grounds for attributing that level of revenue to the 70-seat PIVALDI CITY restaurant. Readers should take care not to conflate figures for venues of different sizes: the large restaurants and the urban format feature in the same article, but that does not make their financial performance interchangeable.
When discussing a franchise purchase, it would be useful to request monthly figures for a comparable venue. This would help establish whether the stated margin reflects sustained performance rather than a particular period. This is a practical due diligence recommendation, not a judgement on the accuracy of the published figures.
How to assess the offer without inflated expectations
PIVALDI’s story brings together two different scales of operation under one brand: established large restaurants and a separate, smaller format for franchisees. The main news for the franchise sector lies in the terms of PIVALDI CITY and the stated direction of expansion, rather than any proven ability to reproduce the wider chain’s results at a small venue.
The Forbes article is labelled as advertising. Its terms and performance figures should therefore be treated as information from a presentation of the offer and an interview with a chain representative, rather than an independent assessment of the financial model. Nevertheless, the published figures provide a concrete basis for further questions.
Before making a decision, a prospective franchisee should agree what the investment covers, obtain an explanation of the payback calculation and examine the Khimki restaurant’s financial performance with all costs taken into account. The basis for calculating royalties also deserves particular attention: the stated rate is linked to revenue.
The practical takeaway is to assess PIVALDI CITY as a standalone format, using its own budget and comparable operating data. The scale of PIVALDI’s large restaurants and its plans to cover Moscow’s districts are no substitute for a financial assessment of a specific franchised site.