Franchise Start-up Loans in South Korea: Checking Approval Conditions and Funding Gaps Before Signing
A franchisor’s offer to help arrange a loan is not lender approval. Before signing a franchise agreement, check the loan conditions, when funds will be released and your liabilities if approval falls through.
Published
For prospective franchisees entering South Korea’s franchise market, a start-up loan is more than a way to cover a funding shortfall. Whether you can meet your contractual commitments depends on when the loan is released and under what conditions. Once you have found a brand you like, resist the urge to sign straight away. Distinguish the franchisor’s funding guidance from the lender’s assessment, and test your funding plan against the dates when payments are actually due.
1. Distinguish ‘help arranging a loan’ from ‘loan approval’
A franchisor introducing a lender or recommending a partner’s financial product does not mean your loan is guaranteed. The maximum amount mentioned during a consultation may also differ from the amount approved for you. When choosing a brand, look beyond claims that finance is easy to obtain. Check whether it is clear who can confirm the conditions that apply to you.
Ask the franchisor for the lender’s name, the loan product, the relevant contact and any fees involved in the introduction. Establish whether the amount quoted is the product’s general lending limit or an estimate based on a review of your documents. Confirm actual approval and drawdown conditions directly with the lender, and keep a record of the consultation date and the answers provided.
Put the following questions to the lender in this order:
- Is my application currently at the initial consultation, preliminary assessment or formal approval stage?
- Are there any further conditions I must meet after approval but before the funds are released?
- If a franchise agreement or lease is required, at what stage must I submit it?
- How long are the approval terms valid, and what circumstances would trigger a fresh assessment?
- Will the loan be paid into my account or directly to the relevant supplier or other party?
The sequence is particularly important for products where assessment only proceeds once a signed agreement has been submitted. Having to sign first does not remove the financial risk. Calculate the deposits and cancellation costs you would be exposed to before formal approval, and proceed only within limits you can afford.
2. Do not mistake government-backed funding guidance for a legal guarantee of support
South Korea’s franchise sector is subject to specific rules under the Fair Transactions in Franchise Business Act. The Act provides protections for prospective franchisees, including requirements governing the registration and provision of disclosure documents and the content of franchise agreements. However, a registered disclosure document does not guarantee approval for a particular loan or the profitability of an outlet.
Article 13 of the Franchise Business Promotion Act is also relevant to start-up support. It allows the government to provide necessary support to people starting franchise businesses and requires measures to provide information on finance, staffing, technology, sales channels and locations. It does not mean that every prospective franchisee will receive a loan or be guaranteed the amount requested.
If you are told about a government funding programme or a loan linked to a guarantee scheme, check the programme’s current announcement and the administering institution’s guidance. Eligibility, permitted uses of funds, application periods and assessment procedures must be checked for each product. If a guarantee is required, ask separately how the guarantee assessment relates to the loan assessment and where each process currently stands.
Do not immediately count the amount you intend to apply for as secured funding in your financial plan. List your own funds, loans with confirmed approval conditions, funding still under assessment and support you have not yet applied for separately. Distinguishing between submitting paperwork and having money available to spend can help prevent you from taking on larger contractual commitments based on uncertain finance.
3. Calculate funding shortfalls by date, not just total start-up costs
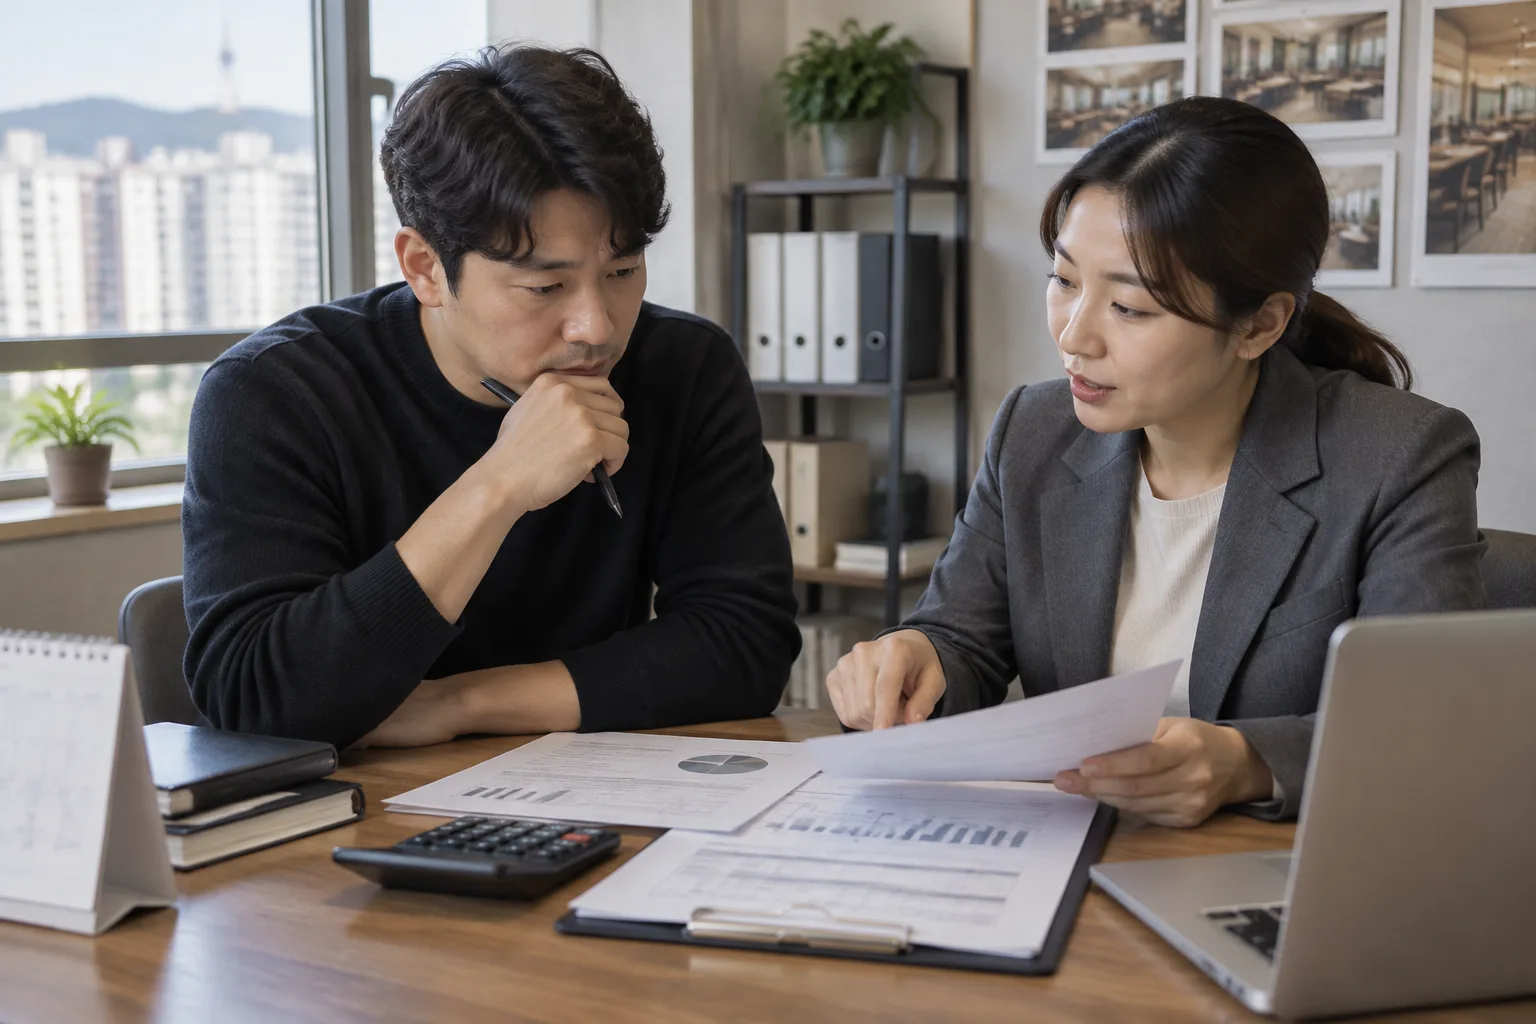
Even if your total costs and loan limit are similar, you may run short of money while preparing to open. An initial fit-out payment might be due before the loan can be released following submission of specific documents. You need more than a comparison of totals: prepare a cash-flow forecast covering the period from signing through the early months of trading.
Start by listing expenses in payment-date order. Separate franchise-related fees, the lease deposit, fit-out costs, equipment and initial stock. For each item, record the deposit, interim payments and final balance separately. Check whether quotations include VAT and whether any costs are excluded from loan funding.
Alongside these expenses, enter the amount of your own money and loan funding that will actually be available on each date. Do not add an undrawn loan to your available balance. Subtract the available funds from cumulative expenditure at each date to identify when you will need additional cash. This is why the timing of a loan’s release can determine whether opening is feasible, even when the loan amount is unchanged.
Keep opening costs separate from working capital. Rent, wages, utilities and supplier payments begin falling due as soon as you open. Even after making sales, you may have to wait for the proceeds to reach your account, depending on the payment method. If you also need to draw money from the business for living expenses, include that amount separately.
Finally, test delays to the loan release and the opening date as separate scenarios. Identify which payment would first leave you short, whether payment dates can be renegotiated and whether another source of funds is available. If the terms of alternative finance are unclear, do not treat it as a confirmed solution. Reconsider the scale or timing of your commitments instead.
4. Check the repayment structure and personal exposure, not just the interest rate
When comparing loans, look beyond the advertised interest rate. Check the costs that actually apply to the product, such as guarantee fees, early repayment charges and costs associated with registering security. When these costs are payable matters as much as what they are called. Charges paid upfront when the loan is released can reduce the cash available just before opening.
The repayment structure also affects how much cash you need each month. Payments may seem manageable during a repayment grace period, but outgoings can rise once principal repayments begin. Obtain a repayment schedule from the lender, separate principal from interest and include both in your monthly cash-flow plan alongside operating costs. For a variable-rate loan, also check how the rate is determined and how often it changes.
Check whether your personal or family assets are involved. Use the contractual documents to confirm who the borrower is, who is providing security and whether anyone has guarantee obligations. If family members contribute funds, clarify whether the money is a gift or a loan, and seek tax and legal advice where necessary.
Closing the outlet does not automatically extinguish the loan debt. Do not assess your ability to repay solely on optimistic sales forecasts. Check whether you could cope if sales fall short and how long you could meet essential expenses without further borrowing.
5. Check your liabilities under each contract if approval falls through
The franchise agreement, lease, fit-out contract and loan agreement are separate contracts. A loan refusal does not automatically cancel the others or entitle you to a refund of everything already paid. Check separately how each contract deals with a failure to secure finance.
When negotiating with the franchisor, landlord or fit-out contractor, be more specific than simply saying, ‘I will cancel if I cannot get a loan.’ Set out the minimum approval amount required, the deadline for confirmation, the evidence to be supplied, which payments will be refundable and how costs already incurred will be treated. This reduces the scope for conflicting interpretations. Make sure the other party explicitly agrees to these conditions.
If a pre-drafted contract term is unfairly disadvantageous, it may need to be reviewed under South Korea’s Act on the Regulation of Terms and Conditions. However, a clause does not automatically become invalid simply because a failed loan application would leave you facing substantial costs. Before paying a large sum, ask a qualified franchise transaction adviser or lawyer to review the relevant contracts together and assess the risks.
Practical takeaway: Before signing, summarise three things on a single page: the lender’s approval conditions, your funding shortfalls by date and your liabilities under each contract if the loan falls through. If any of these remains unclear, obtain further confirmation first and be cautious about payments that may be difficult to recover.