Buying a Franchise: Clarify the Rules on Audits and Outlet Inspections
Check inspectors’ authority, audit costs and how to challenge findings before signing a franchise agreement in Indonesia.
Published
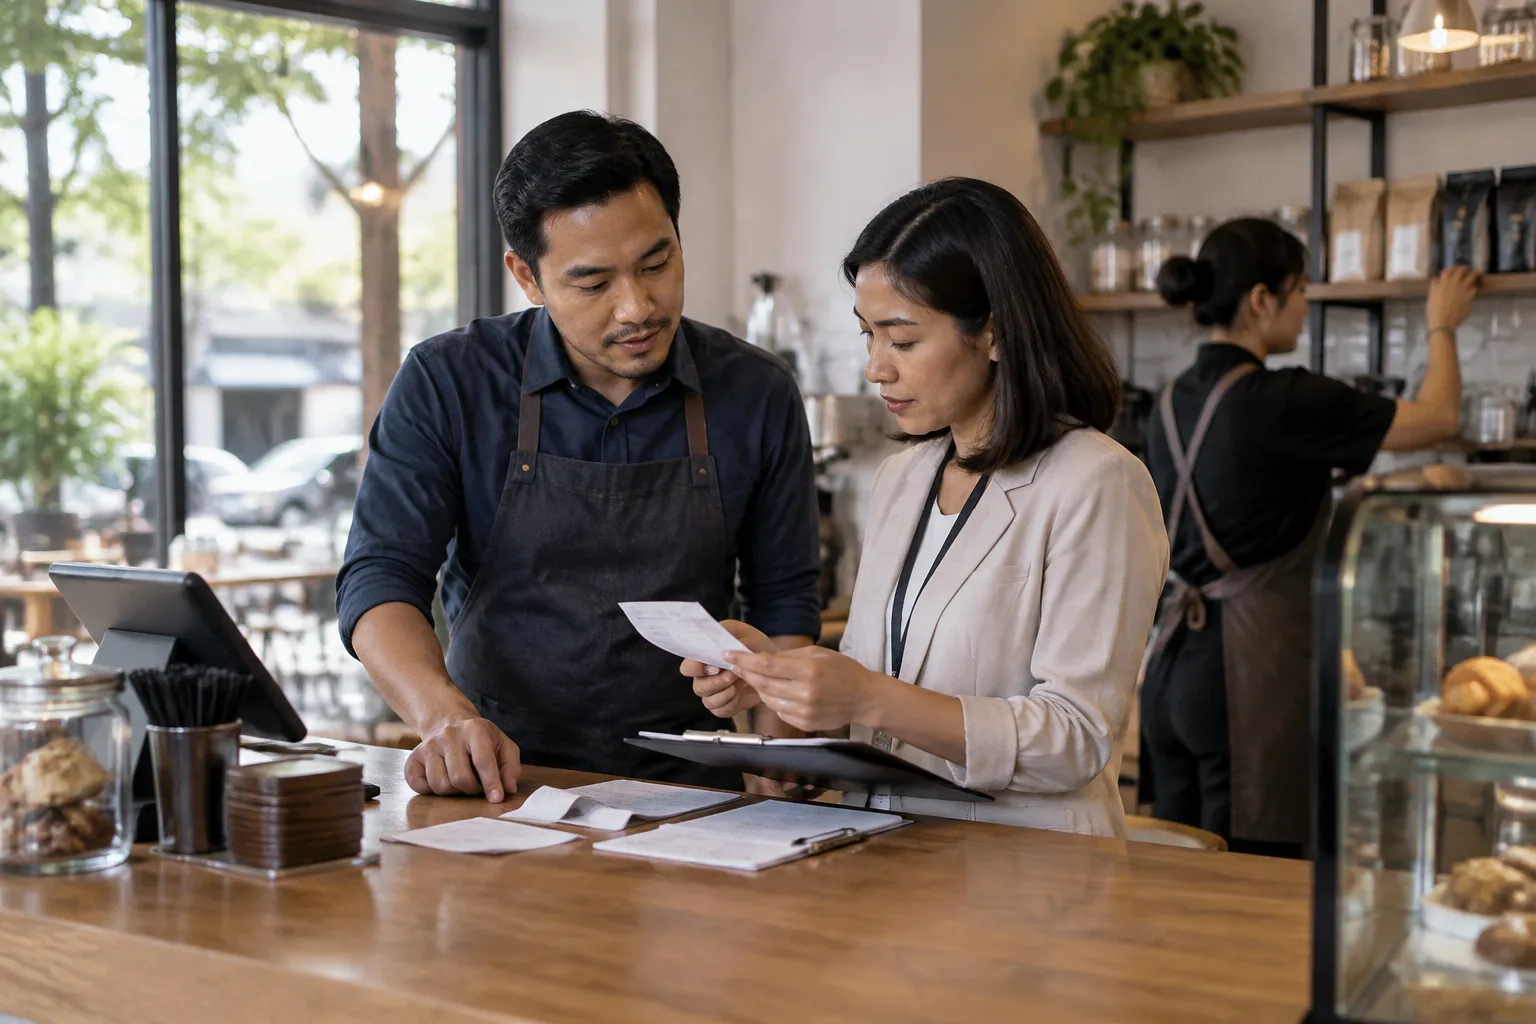
Outlet inspections help maintain quality across a franchise network. However, a clause allowing the franchisor to inspect anything, at any time, with all costs borne by the franchisee can create risks that are difficult to quantify. Before buying a franchise, make sure the agreement sets out not only the right to conduct audits, but also the limits of inspections, how costs are allocated and the franchisee’s opportunity to respond to the findings.
1. Distinguish quality inspections from financial audits
The term ‘audit’ is often used for several different activities. A kitchen hygiene inspection does not require the same documents as a check on the basis for royalty payments. Ask the franchisor to distinguish between the types of inspection in the draft agreement or the inspection guidelines it refers to.
At a minimum, identify these three categories:
- Operational inspections: product quality, hygiene, workplace safety and compliance with service standards.
- Transaction audits: reconciliation of sales, voided transactions, refunds and payments due to the franchisor.
- Special inspections: investigations into serious complaints or specific suspected breaches.
For each category, ask who will conduct the inspection, which documents they may request, how long it will take and what the franchisee will receive afterwards. Request sample checklists and anonymised reports that do not reveal the identity of other outlets.
Be wary of wording such as ‘all documents deemed necessary’ without a link to the purpose of the inspection. If you run several businesses, the accounts of your other businesses should not automatically fall within the scope of a franchise outlet inspection. Propose limiting access to records relevant to the performance of the agreement.
2. Put audit powers in their legal context
Indonesia specifically regulates franchising through Government Regulation No. 35 of 2024 on Franchising, which replaced Government Regulation No. 42 of 2007. This framework covers matters including franchise criteria, offering prospectuses, agreements and the Franchise Registration Certificate, known locally as the STPW.
Government Regulation No. 35 of 2024 also places the parties to a franchise agreement on an equal legal footing and provides for Indonesian law to apply. Prospective franchisees should therefore treat inspection clauses as part of a contractual relationship they need to understand, rather than simply as internal brand rules that cannot be questioned.
The general requirements for a valid agreement remain those set out in Article 1320 of the Indonesian Civil Code: consent, legal capacity, a specific subject matter and a lawful purpose. However, the existence of franchise regulations does not mean that the government has automatically determined every detail of the audit process.
Limits on frequency, notice requirements, cost allocation and response procedures need to be clarified in the agreement. Do not assume that franchisees automatically have the right to refuse unannounced inspections or to have inspections carried out free of charge. Equally, do not accept claims that every request from an inspector is a legal obligation without asking for the specific legal basis.
Before signing, ask a legal adviser to assess whether the audit powers are proportionate to their purpose and consistent with applicable confidentiality and data protection obligations.
3. Calculate potential costs and disruption
Inspection costs are not limited to an auditor’s invoice. You may need to make staff available, retrieve records, carry out stocktakes outside working hours or suspend part of your service. All of this can affect the outlet’s cash flow.
Request written clarification on the following points:
- Who pays for routine inspections scheduled by the franchisor?
- When can the cost of a special inspection be passed on to the franchisee?
- Are travel, accommodation and third-party service costs included?
- Is there a charge for re-inspections, and how are the rates determined?
- Is there a cost cap or a requirement to obtain approval in advance?
As a negotiating point, the cost of a special audit could be linked to substantiated findings rather than mere suspicion. If a transaction discrepancy threshold is used to trigger cost recovery, the calculation and measurement period must be clear. Avoid terms such as ‘material discrepancy’ without a definition.
Also agree how inspections will be carried out at the outlet. Scheduled inspections can take place at times that minimise disruption to customers. For unannounced inspections prompted by safety risks or suspected fraud, specify the grounds for making an exception, how inspectors will identify themselves and the arrangements for an outlet representative to accompany them. The aim is not to obstruct oversight, but to prevent unnecessary disruption.
4. Make sure findings can be checked and challenged
An audit report may form the basis for additional charges or action under the agreement. Do not assess only how inspectors gain access to the outlet; also examine how their findings are established.
Propose that written reports specify the standards applied, the period examined, supporting evidence, calculation methods and an explanation of each instance of non-compliance. For sample-based audits, ask how samples are selected and whether the results will be extrapolated across the entire sales period.
Franchisees should have an agreed period in which to respond and submit evidence to counter the findings. For example, an apparently missing transaction may actually be a legitimate cancellation or a duplicate entry. The agreement needs to distinguish preliminary findings from final conclusions reached after clarification.
Request a review mechanism involving someone other than the original inspector where there are reasonable grounds for an objection. Also clarify whether the outlet manager’s signature merely acknowledges receipt of the report or indicates agreement with its entire contents. Do not allow staff to accept payment obligations without authority.
Practical step: before buying, request a sample audit report and an illustration of the charges that could follow. Proceed only once the purpose of inspections, access limits, costs and response procedures are set out clearly and reasonably in writing.
Sources
- Bisnis Franchise di Indonesia dari Masuk hingga Aturan Baru
- [PDF] KEBIJAKAN WARALABA - JDIH Kementerian Perdagangan
- bahwa dalam yang - jdih.kemendag.go.id
- Jurnal Lex Suprema
- PERATURAN PEMERINTAH REPUBLIK INDONESIA
- BERITA NEGARA REPUBLIK INDONESIA - peraturan.go.id
- Microsoft Word - 97pp016
- Aspek Hukum dalam Perjanjian Waralaba (Franchise)