Buying a Franchise Business: Check the Equipment and Stock
The balance sheet alone will not tell you what equipment and stock are worth. Check ownership, condition and saleability before buying a franchise business.
Published
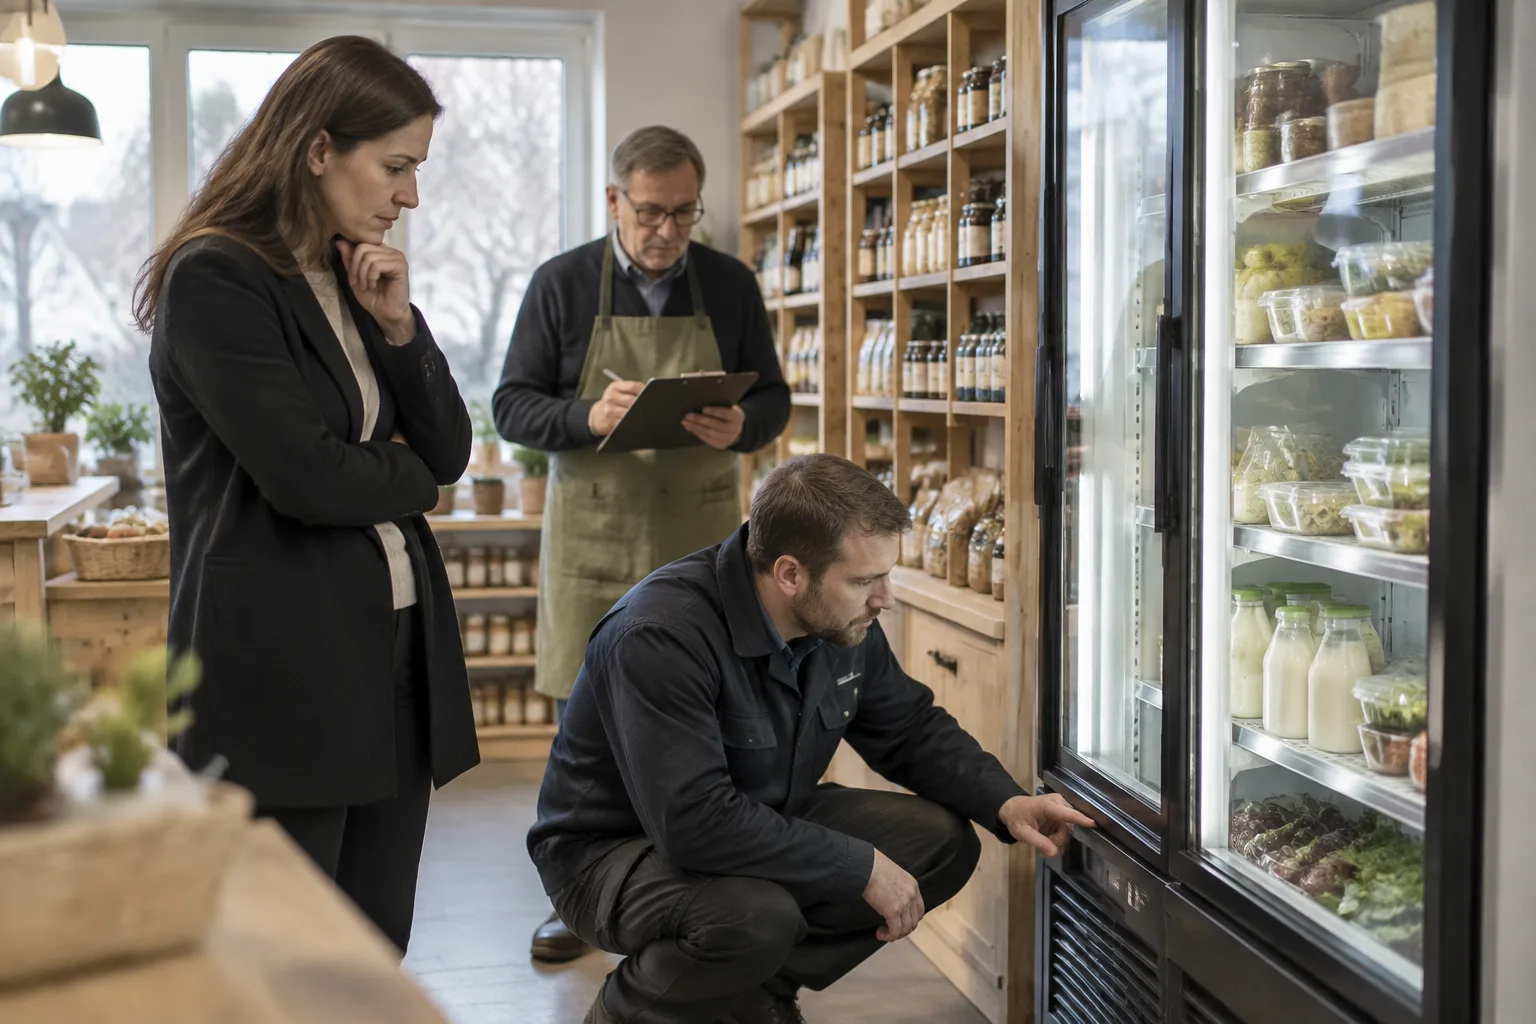
When buying an established franchise business, familiar branding and fully stocked shelves can look like a ready-made start. Even so, you need to establish exactly what you are getting and how much additional spending the assets will require immediately after completion. A franchise network consists of independent businesses: its branding does not guarantee the condition of an individual outlet’s equipment or the saleability of its products. Treat equipment and stock checks as a separate part of your due diligence before making a binding commitment to buy.
1. Define what you are buying and verify ownership
Start by distinguishing between a share purchase and an asset purchase. In a share purchase, you buy the company’s shares, while its equipment and stock remain the property of that same company. Its debts and contractual liabilities also remain with it. In an asset purchase, the assets being acquired are specified in the sale agreement; not everything on the premises is automatically included.
Ask for an equipment list showing each item’s name, identifying details, acquisition date, location and stated owner. Compare the list with the fixed asset records, purchase invoices, and finance and lease agreements. Walk through the premises with the seller, noting separately any equipment that is missing, out of use or located elsewhere.
The outlet may contain, for example:
- machinery, furniture and fittings owned by the selling company
- equipment owned by a leasing company
- refrigeration units on loan from a supplier
- till terminals owned by the franchisor
- assets bought on instalment terms subject to retention of title.
Possession of equipment does not, on its own, establish ownership. With professional advice, also investigate any security arrangements and Finnish enterprise mortgages affecting the assets. If an asset purchase is intended to include the transfer of a lease or maintenance agreement to you, check directly with the other contracting party whether it can be transferred and what consents are needed.
Also record who is responsible for software licences and the transfer of usage rights. A working till may be practically useless if you cannot access its essential software after completion.
2. Assess practical value, rather than relying on the balance sheet
Book value is not the same as fair value or value to your business. Fully depreciated equipment may still have years of service left. Conversely, a machine with a substantial balance sheet value may be nearing the end of its useful life or be unnecessary for the business you are buying.
Ask for maintenance histories, inspection reports and details of recurring faults. Where necessary, have a qualified service engineer check whether the equipment works under normal operating loads. Investigate spare parts availability, any remaining warranties and whether maintenance services can continue. The seller’s verbal assurance that equipment is in “good condition” is no substitute for a documented inspection.
Also obtain written confirmation from the franchisor that the existing equipment is suitable for continued use within the franchise concept. The purpose of this check is not to assess general rights to amend the franchise agreement, but to establish whether the specific equipment you are buying is usable in the planned business.
Include separate lines in your acquisition budget for immediate repairs, replacements needed in the near future and potential downtime. Allow for dismantling, transport, installation and proper disposal of old equipment too. A cheap second-hand machine can prove expensive if replacing it interrupts sales.
Give your lender the same equipment list and condition information that you use to assess the price. The value a lender accepts as security may differ substantially from the purchase price. Do not base your financing plan on the assumption that the equipment’s collateral value will cover its full purchase price.
3. Count the stock and agree the valuation method in advance
Stock quantities and quality change daily. The stock figure in the financial statements is therefore not enough on its own to establish the purchase price. Agree on a joint stocktake as close as possible to handover, and define how purchases, sales and wastage between the stocktake and handover will be treated.
As well as counting the products, check their condition and whether they can realistically be sold. Identify expired products, damaged packaging, slow-moving lines and discontinued products separately. Establish whether all the products belong to the company or whether the stock includes, for example, goods held on consignment that still belong to a supplier.
Agree at least the following in writing:
- which product categories are included in the stock being purchased
- the price at which accepted products will be valued
- how discounts, return rights and obsolete or unsaleable stock will be treated
- who will carry out the stocktake and how disputes will be resolved
- how the final stock valuation will affect the purchase price payable.
For example, the original purchase cost of a seasonal product may not reflect its value once the season has ended. Ask for stock turnover data for each product line and compare it with the physical stock. If that information is unavailable, the uncertainty should be reflected in the price or the terms of the deal, not just in your notes.
4. Incorporate the findings into the sale agreement
Finland has no specific franchise legislation, no statutory franchise disclosure form and no requirement to register franchise agreements with a public authority. Agreements within franchise networks are governed by legislation including the Finnish Contracts Act, the Unfair Business Practices Act and competition law. The European Code of Ethics for Franchising is a form of self-regulation, not legislation or an official guarantee of the business you are buying.
The Finnish Sale of Goods Act may also apply to the sale of equipment and stock. In business-to-business transactions, however, the contractual terms carry considerable weight. The buyer’s inspection and any defects already known to them may affect their ability to make a subsequent claim for defects. It is therefore important to document both the inspection findings and the agreed way of addressing them.
Attach the agreed asset lists, condition information and stock valuation principles to the sale agreement. Agree on the seller’s warranties concerning ownership and the information supplied, as well as the procedure to follow if deficiencies are found at handover. A lawyer can help define clear terms for price adjustments, responsibility for repairs or withholding part of the purchase price.
Practical checklist: do not pay for assets based solely on the balance sheet or a tour of the premises. Verify ownership, test fitness for use, take stock and incorporate every finding that materially affects the price into the sale agreement.
Sources
- Q&A: offer and sale of franchises in Finland
- KYMENLAAKSON AMMATTIKORKEAKOULU
- Yrityksen ostaminen - Muutokset ja kriisitilanteet - Suomi.fi
- Yrityksen ostaminen
- Sopimusjuridiikkaa, yhtiöoikeutta ja immateriaalioikeuksia ...
- Yrityksen tai osakkuuden ostaminen - Muutokset ja kriisitilanteet - Suomi.fi
- Onnistunut omistajanvaihdos
- Franchising