Buying a Franchise in South Africa: Opening Stock Checks
Check how opening stock is priced, counted and paid for before buying a South African franchise, whether new or already trading.
Published
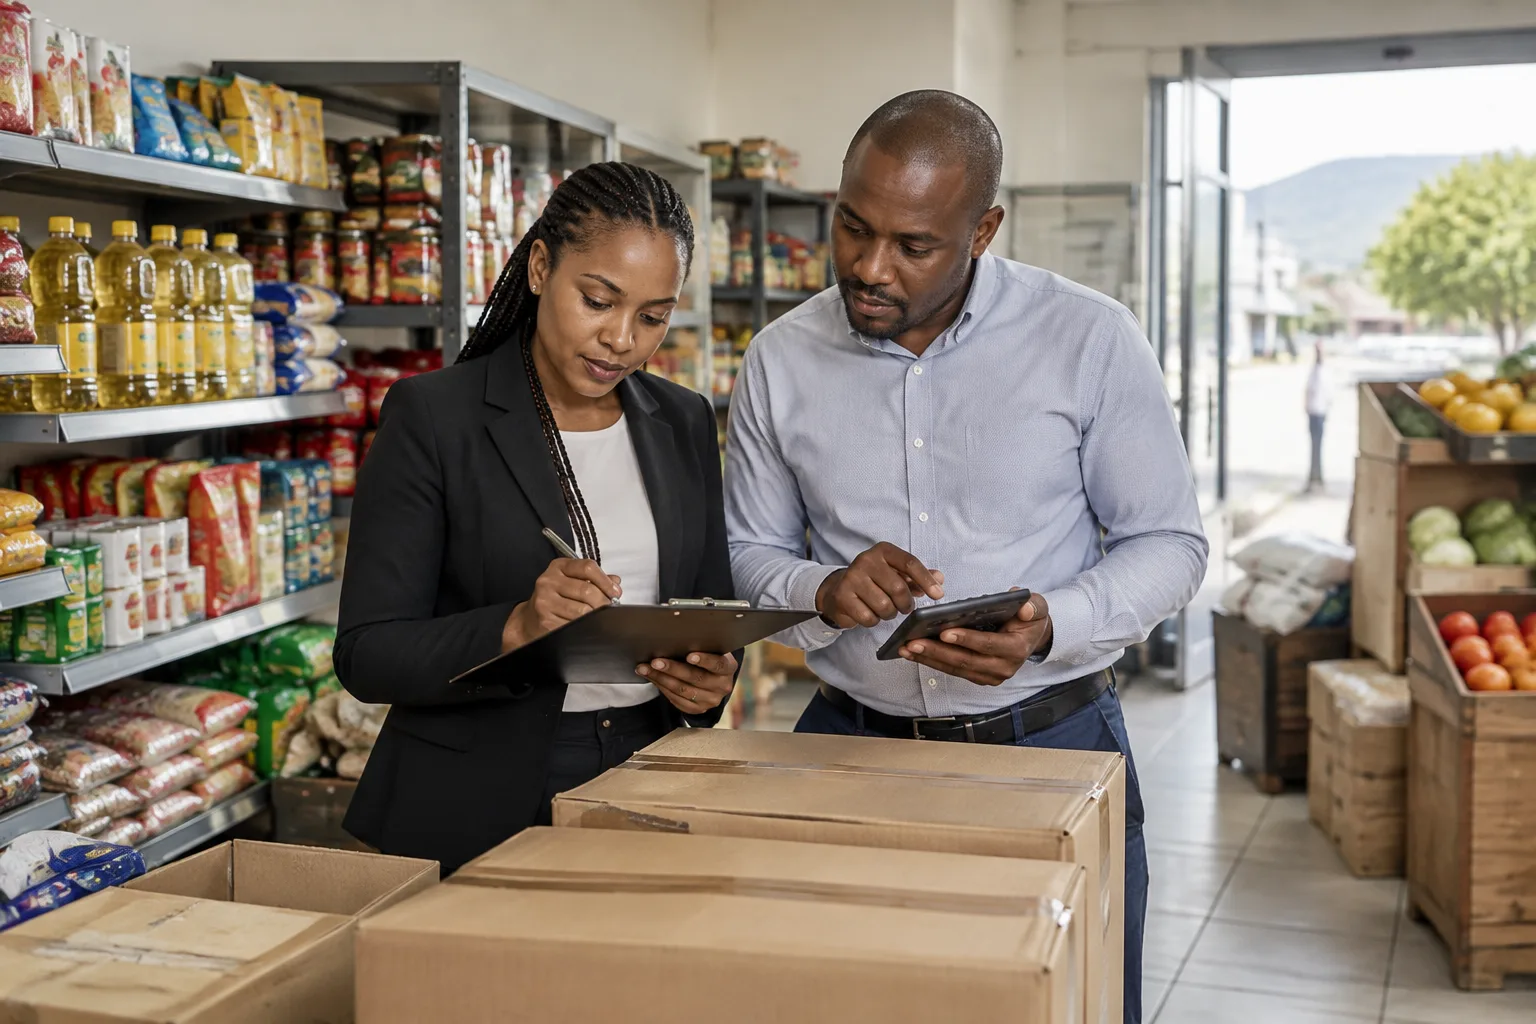
Opening stock can turn an apparently affordable franchise into a more expensive purchase. Whether you are launching a new outlet or buying an existing one, you need to know exactly what inventory you will receive, how it is valued and whether it can realistically sell. Within South Africa’s franchising community, a familiar brand is no substitute for checking the goods behind the purchase price.
1. Establish what the stock payment covers
Ask for an itemised opening-stock schedule rather than accepting a single figure labelled “stock included”. It should identify quantities, unit prices and the distinction between goods for resale, ingredients, packaging and operating consumables.
For a new outlet, establish who determines the initial order. A standard opening package may simplify launch preparations, but you should still ask how its quantities relate to your outlet’s format, storage capacity and expected demand.
For an existing outlet, clarify whether the advertised purchase price includes inventory or whether stock is payable separately after a handover count. An indicative estimate is not the same as an agreed maximum liability.
Ask these questions before committing:
- Does the quoted amount include VAT, delivery and handling?
- Are display items, testers or promotional giveaways included?
- Is any inventory held on consignment rather than owned by the seller?
- Can quantities or prices change before delivery or handover?
- Who pays for shortages, damaged deliveries or incorrect orders?
Record the answers in the relevant purchase documents. A verbal promise that the outlet will be “fully stocked” leaves too much room for disagreement.
2. Agree a valuation method before counting
A stock count establishes quantity; it does not establish value. Agree the valuation method before anyone starts counting shelves or opening cartons.
For an existing business, ask the seller to support unit costs with supplier invoices and explain how discounts, returns and credit notes affect those costs. Do not accept shelf selling prices as evidence of what inventory should cost you: those prices include a margin you have not yet earned.
Your accountant should help you distinguish ordinary saleable stock from items requiring a reduction or exclusion. Check particularly for:
- Expired goods or products approaching their expiry dates.
- Damaged packaging, incomplete sets and customer returns.
- Discontinued lines or goods no longer approved for sale under the brand.
- Seasonal products unlikely to sell before the next buying cycle.
- Excess quantities unsupported by recent sales records.
For a new outlet, request the proposed order alongside the assumptions used to size it. Ask whether slow-moving items can be exchanged and obtain any return conditions in writing. Do not assume a supplier must take back unsold goods simply because the opening package was recommended.
3. Put the stock arrangements into the right contracts
South African franchising is specifically regulated through the Consumer Protection Act 68 of 2008 and its Regulations, although there is no separate standalone franchise statute. Common law also governs contractual obligations.
Regulation 2 requires franchise agreements to set out prescribed financial information, including the funds needed to establish the business and opening-stock costs. Regulation 3 requires a prospective franchisee to receive the prescribed disclosure document at least 14 days before signing the franchise agreement.
These requirements help you understand the investment, but they do not replace a detailed stock arrangement. When buying an existing outlet, the seller’s inventory obligations may sit in a separate business sale agreement. Have your attorney check that it agrees with the franchise documents and does not leave responsibility unclear.
Specify the valuation basis, excluded goods, payment date and procedure for resolving count discrepancies. If the final stock bill is uncertain, negotiate a spending ceiling or an approval process for any excess. Also establish when ownership and the risk of loss pass to you, and arrange insurance accordingly.
4. Control the count and handover
Agree who will attend the count and when it will happen. If trading continues during counting, record subsequent sales, deliveries, returns and wastage so the final schedule reflects what actually transfers.
Count goods in storerooms, cold rooms and off-site storage as well as on the shop floor. Separately identify inventory belonging to suppliers or other parties. Photograph disputed or damaged items and obtain a jointly signed schedule rather than relying solely on the seller’s accounting system.
For a new outlet, reconcile delivered goods against both the approved order and the invoice before accepting that the opening package is complete. Report discrepancies within the applicable contractual deadlines.
Practical takeaway: Before paying for opening stock, agree what you are buying, how it is valued and how delivery or handover will be verified. Pay for a documented inventory, not an assumption about full shelves.
Sources
- Legal Guide to Buying a Franchise in South Africa
- The legalities of franchising | Capitec Bank
- How to succeed in a franchise business
- What to consider before buying a franchise - Old Mutual
- [PDF] Chapter 33 Franchising - Oxford University Press Southern Africa
- South Africa: Franchise & Licensing
- South Africa's Booming Franchise Industry: Your Ticket to Business Success
- Franchise Laws and Regulations Report 2026 South Africa - ICLG.com