
How to Present Earnings Projections to Prospective Franchisees in India
Before sharing earnings projections with prospective franchisees in India, make the data, costs and risks clear. Follow this practical approach to credible disclosure.
Published
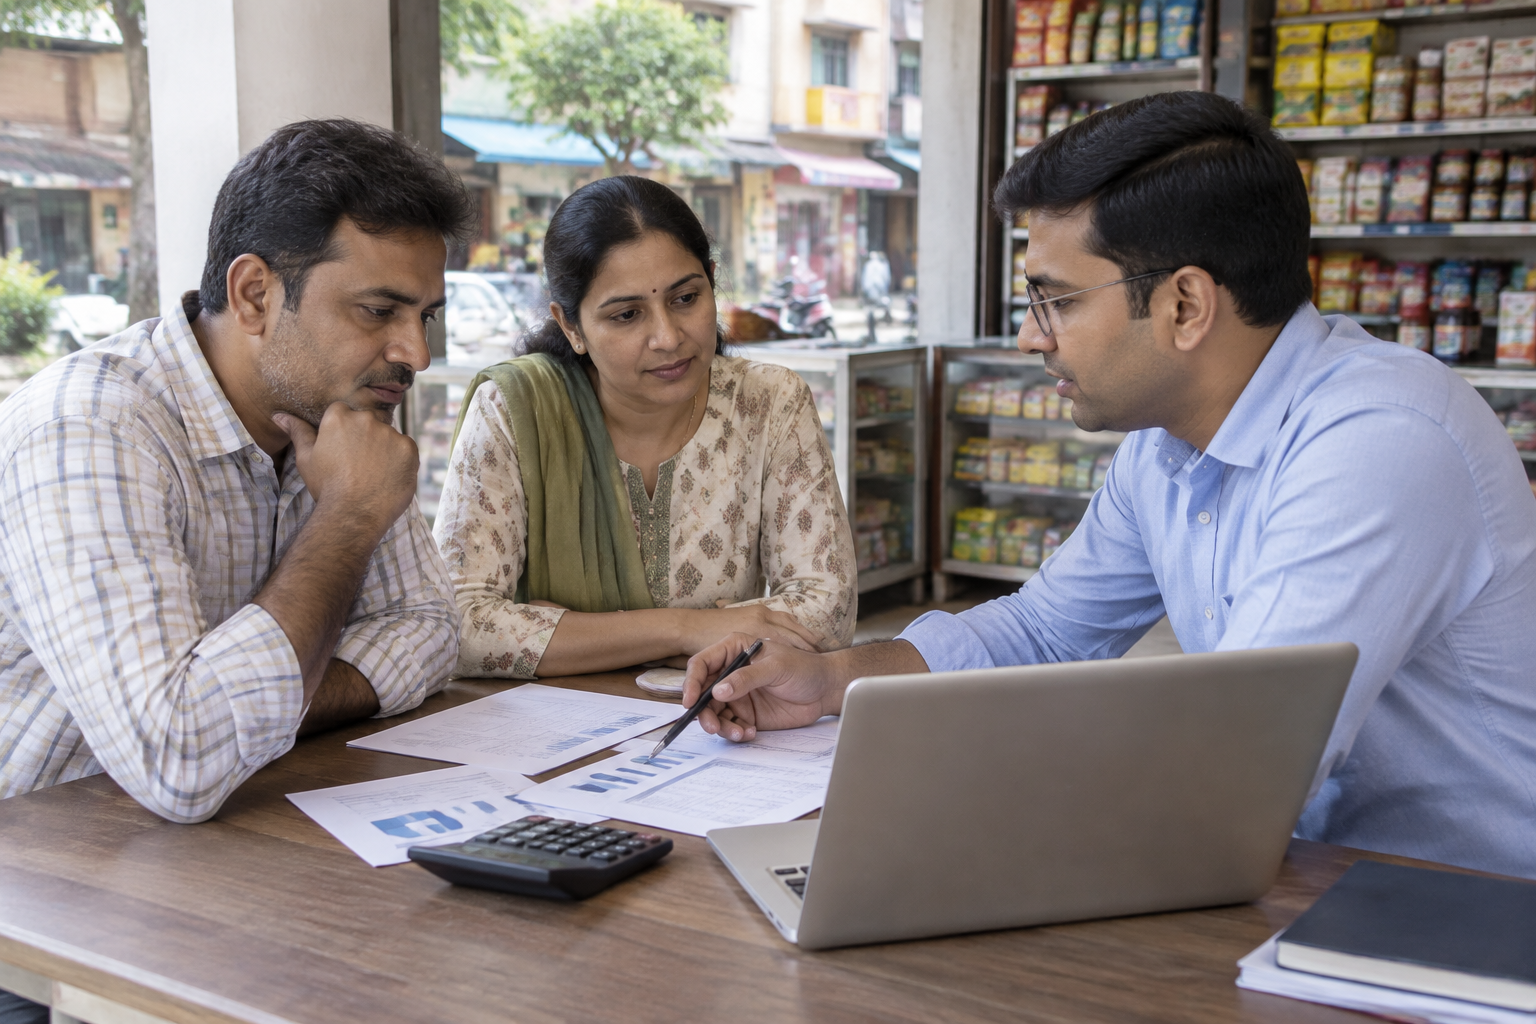
When you franchise a successful business, a prospective partner’s first question is often: ‘How much profit will I make?’ The earnings of your existing outlet do not provide a straightforward answer. Rent, customer numbers and operating capacity will differ at a new location. An earnings projection should therefore be a decision-making document based on evidence and clear assumptions, not a sales promise.
1. Understand the law: no mandatory format does not mean misleading claims are permitted
India has no dedicated central franchising law, separate government franchise registry or mandatory pre-sale disclosure document requirement. US franchise disclosure rules do not automatically apply to domestic franchise offerings in India. Nor is there a general, franchise-specific statutory waiting period for providing information.
However, this does not mean you can make unsupported promises of profit. The provisions on fraud and misrepresentation in the Indian Contract Act, 1872 are relevant. Consent obtained through misrepresentation may provide grounds for challenging a contract; the consequences will depend on the circumstances and applicable provisions.
Within the wider legal framework, the Trade Marks Act, 1999 concerns brand rights, the Competition Act, 2002 addresses anti-competitive restrictions, and the Consumer Protection Act, 2019 relates to obligations towards customers. A commercial investor buying a franchise is not automatically treated as a consumer. Tax, employment and sector-specific rules also apply separately.
The practical approach is to provide written earnings information voluntarily and have its claims reviewed by a lawyer. Do not present it as government approval or a guarantee of profit.
2. Build a file of comparable data before preparing projections
Do not use your best sales month or most successful outlet as representative of the entire network. First establish the size, location and operating format of the proposed franchise. Then select data from comparable outlets.
Keep the following information alongside each set of figures used:
- Source: point-of-sale systems, accounting records, purchase invoices or bank reconciliations.
- Period: which months the results cover, and whether they included festivals or opening promotions.
- Sample: how many outlets are included, which are excluded and why.
- Operating status: whether the outlet is company-operated or franchised, and whether it is new or established.
- Unusual circumstances: rent-free premises, unpaid work by the owner or special supplier discounts.
If you have only one company-operated outlet, state this clearly. Do not present its results as proven across several franchised outlets. Excluding closed or underperforming outlets without explanation can create a misleading picture.
Have an accountant reconcile the figures. If they have only been checked internally, do not describe this as an independent audit.
3. Show sales, profit and cash separately
A vague term such as ‘monthly earnings’ in a franchise recruitment presentation can lead to disputes. Specify whether the figure shown is sales revenue, gross profit, operating profit or the amount remaining after all relevant expenses.
Include the cost of goods, rent, wages, electricity, local marketing, delivery platform fees, maintenance and wastage in the projections. Also include the proposed royalty, brand marketing contribution, mandatory technology fees and reasonable remuneration for the owner’s work. Even if a company-operated outlet pays no royalty, you must show its impact in the franchise model.
Profit is not the same as available cash. Opening stock, deposits, delays in customer payments and loan repayments can change cash requirements. Show initial investment and working capital separately, and have a specialist check the tax treatment.
Rather than presenting a single attractive outcome, show downside, base-case and upside scenarios. For each scenario, state the assumptions for customer numbers, average transaction value, rent and costs. If you calculate an investment payback period, explain the calculation and the expenses included. Phrases such as ‘guaranteed return’ can amount to unsupported assurances.
4. Link every recruitment claim to the documentation
An accurate document is not enough if a sales representative makes a different promise over the phone. Establish a consistent set of approved claims for advertising, messages, presentations and one-to-one conversations.
Record the version, date and responsible manager on every financial presentation. Instruct the sales team not to give assurances about profit, payback periods or customer numbers beyond the approved parameters. Apply the same controls to external franchise recruitment agents.
If a candidate asks, ‘How much profit will I make in my city?’, do not give a definite answer without investigating local rent, wages and demand. If the projection changes, share its revised basis in writing. Adding a small disclaimer at the bottom does not automatically correct a misleading claim made above it.
5. Establish a review and record-keeping process before taking payment
Adopt an internal policy that gives candidates enough time to read the financial information, fee schedule and proposed agreement before making a significant payment or signing. This is good business practice, not a mandatory Indian franchise disclosure timetable.
Allow candidates to seek independent legal and financial advice. Keep a written record of their questions and your answers. If there is a material change before signing, provide revised information and another opportunity to review it. Obtain confirmation of receipt, but do not treat this as a release from responsibility for inaccurate information.
Practical takeaway: gather evidence first, include the full costs, and then provide projections with their limitations clearly stated. Credible franchise recruitment rests on verifiable information, not promises of substantial earnings.
Sources
- India
- How to Register a Franchise Business in India: Legal Framework ...
- Franchise Business Registration in India 2026
- Franchise Laws And Regulations India 2025. - Conventus Law
- Franchise Agreement And Its...
- Franchise Law in India: Guide for Franchisors & Franchisees
- अपने व्यवसाय को फ्रैंचाइज़ (Franchise) कैसे दें: छोटे व्यवसायों के लिए 7 कदम - Shabd Prabhat
- क्या होती है फ्रेंचाइजी? इसे लेकर कैसे खड़ा करें शानदार बिजनस, एक्सपर्ट्स ...