Buying an Existing Franchise: Auditing and Valuing Stock
Before buying an existing franchise, check stock ownership, condition and value to negotiate a fair price and avoid being left with unsold goods.
Published
When buying an existing franchised business, stock may seem secondary to the price of the business itself. Yet goods that cannot be sold, are incorrectly valued or belong to a supplier can significantly change the true cost of the deal. Joining a franchise network does not remove the need for this audit: before negotiating, you need to know exactly what you are buying and under what conditions you will be able to sell it.
1. Establish which stock is actually included in the acquisition
Start by clarifying the acquisition structure with your lawyer and accountant. In a French business asset sale (cession de fonds de commerce), stock is generally inventoried and valued separately. In a share acquisition, it remains an asset of the company being acquired; its value nevertheless affects the price and any adjustments provided for in the agreement.
Ask the seller for a detailed stock list showing the quantity, purchase cost, date received and location of each product line. Reconcile this list with supplier invoices and accounting records. A balance sheet total alone does not establish the current value of the goods on hand.
Also check who owns the goods. Items held on consignment do not necessarily belong to the retailer. A retention of title clause may also mean that ownership remains with the supplier until payment has been made in full. Identify unpaid invoices and ensure the agreement specifies how they will be dealt with.
Finally, distinguish goods intended for sale from equipment, samples, packaging and items entrusted to the business by customers. Each category needs appropriate treatment, without being counted twice in the price.
2. Assess saleability, not just quantities
A product that is physically present is not necessarily a useful asset. Analyse the age and turnover of each product line using actual sales records. Identify goods that have remained unsold for a long time, as well as items already allocated to customer orders.
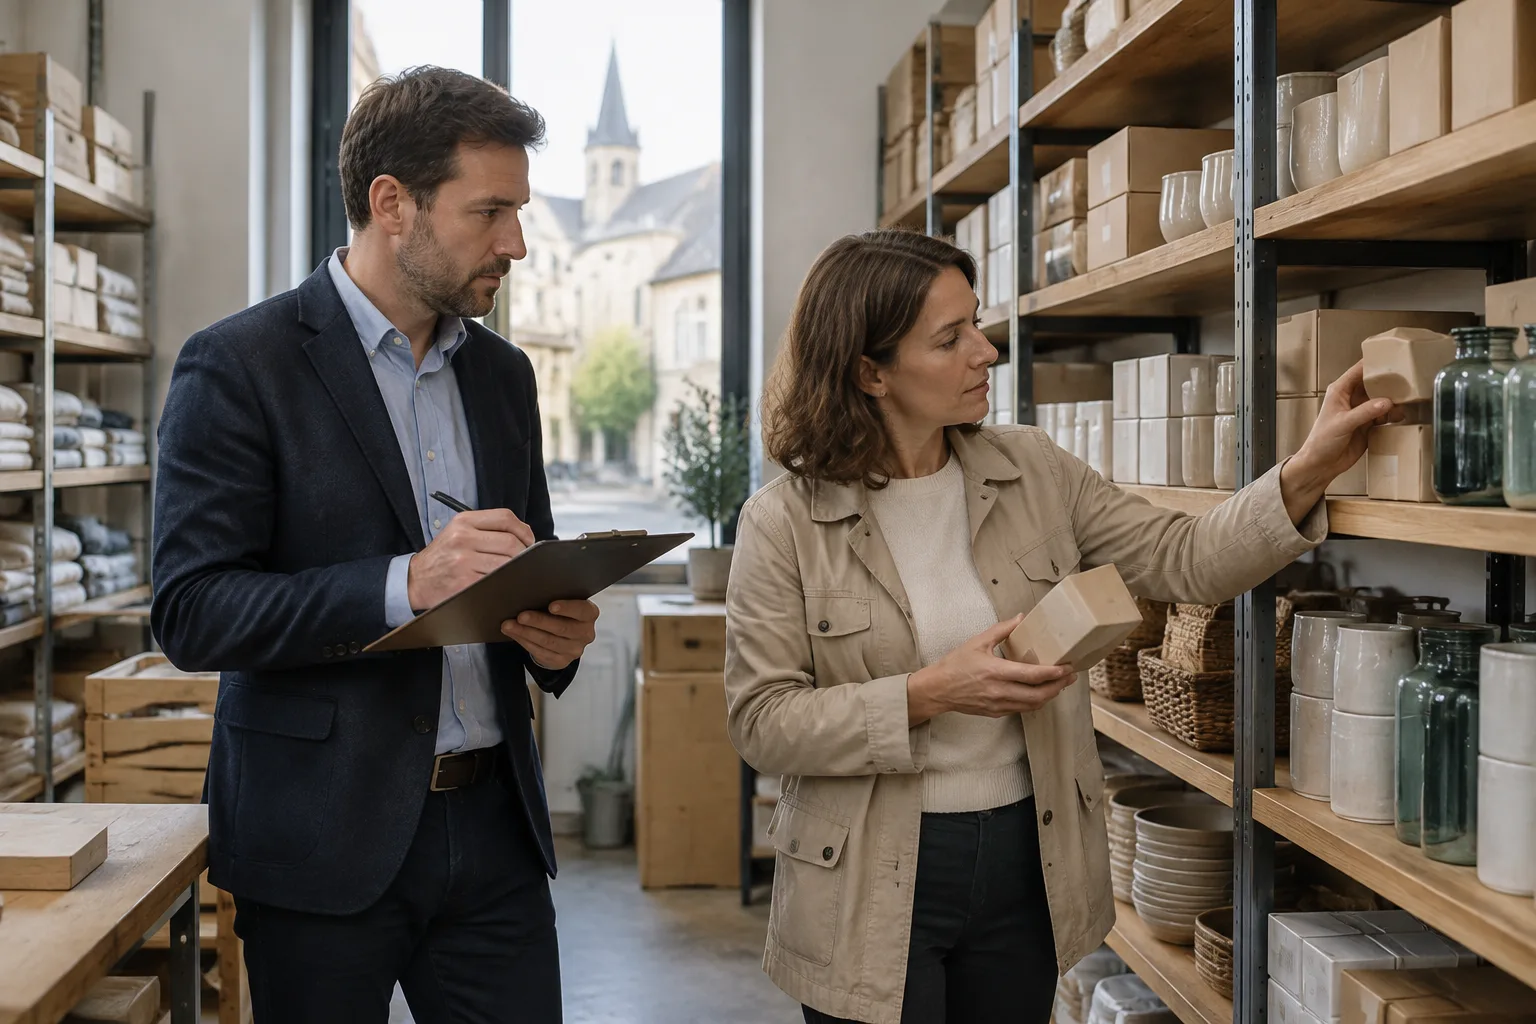
Arrange to inspect the stockrooms, not just the shop floor. Depending on the business, check in particular:
- expiry dates and storage conditions;
- damaged packaging, incomplete products and customer returns;
- older collections or discontinued lines;
- products subject to a recall or sales restriction;
- seasonal items whose selling season has passed.
The franchise adds another check: will the stock still be saleable under the brand after the takeover? Ask the franchisor whether any changes to the range, presentation or concept are already planned. Even an undamaged product may become less attractive if the network stops offering it or if selling it would conflict with the buyer’s contractual obligations.
Do not assume that the franchisor or supplier will take back unsold stock. Obtain the applicable terms in writing: eligible products, deadlines, deductions from the credited value, transport arrangements and who will receive the credit note.
3. Agree a verifiable valuation method
The retail price displayed in the shop is not the value of the stock you are acquiring. Work with your accountant to develop a method based on documented costs and realistic sales prospects. Take account of relevant supplier discounts and the expenses included in the acquisition cost.
Set separate rules for current, older, damaged and unsaleable goods. Any reduction in value should be supported by concrete evidence, rather than an arbitrary percentage. Excluded products should be identified, with a clear allocation of removal or disposal costs.
Also set controls on purchasing between agreeing the price and completing the sale. Without these, the seller could substantially increase orders, leaving you with more stock than you need. Depending on the deal structure, negotiate a cap or require prior approval for purchases outside the ordinary course of business.
Finally, assess the total cash outlay: payment for the stock acquired, initial orders and payment terms. Stock presented as a bargain can tie up funds needed to run the business for a long time.
4. Put stocktaking procedures and commitments in writing
Arrange a joint stocktake as close to completion as possible, with both parties or their representatives present. Define how stock movements will be handled during the count, the procedure for resolving disputes and, if necessary, the use of an independent third party. The sale agreement should specify the formula for calculating the final price and the supporting records to be retained.
The French franchise legal framework also remains relevant. Where its conditions apply, Article L. 330-3 of the French Commercial Code, introduced by the Doubin Law, requires the pre-contractual disclosure document (document d’information précontractuelle, or DIP) and draft contract to be supplied at least twenty days before signing or making any required advance payment. Article R. 330-1 sets out the information required. This obligation does not, however, replace an audit of the seller’s stock.
Key takeaway: do not pay for stock solely on the basis of an accounting total. Insist on a verifiable stocktake, a written valuation method and explicit arrangements for unsold goods before committing.
Sources
- Guide pour l'achat d'une franchise
- www.cote-azur.cci.fr · app · uploadsLE GUIDE MALIN DE LA FRANCHISE - cote-azur.cci.fr
- www.gouache.fr · ressources · devenir-franchiseurDevenir Franchiseur : les étapes juridiques incontournables
- propulsebyca.fr · franchise · achatAcheter une franchise en 2026 : Guide complet en 6 étapes
- Racheter une franchise : le guide étape par étape - Orange Pro
- Comment racheter une franchise à un franchisé - Big Media
- Devenir franchisé : les questions à se poser
- Tout savoir pour s'installer en franchise