Eezy’s network sales grew, but EBITDA fell
Eezy’s network-wide turnover rose to €65.5 million in July–September. Growth from a franchisee-led project changed the sales mix.
Published
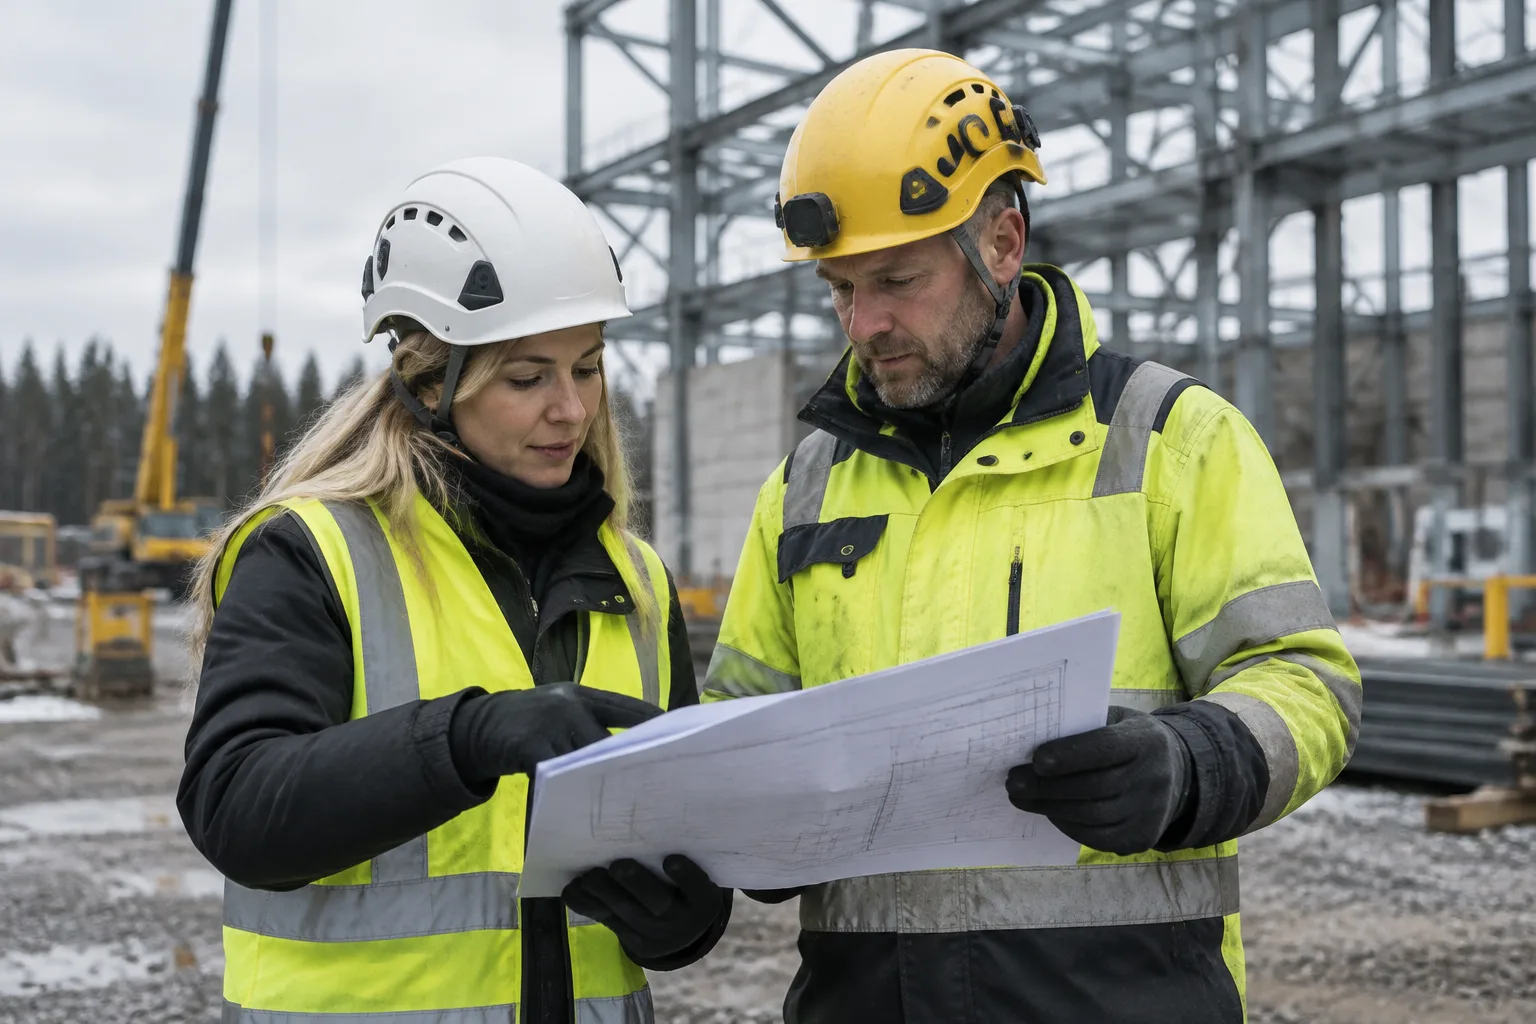
Eezy’s network-wide turnover grew in July–September 2026, but the company’s EBITDA fell year on year. Turnover across the network, including franchisees, rose to €65.5 million. According to a report published by Finnish financial publication Arvopaperi on 5 November, growth was driven by a franchisee-led industrial construction project that changed the sales mix. The results show why network growth and company profitability need to be assessed separately.
Network-wide turnover rose to €65.5 million
Eezy’s total network turnover was €65.5 million in the third quarter, compared with €62.2 million a year earlier — an increase of €3.3 million. This figure includes franchisees’ turnover and therefore covers a broader business base than Eezy’s own reported turnover.
The company’s turnover rose to €37.1 million over the same period, up from €35.5 million a year earlier. That represents an increase of €1.6 million. Both network and company turnover therefore grew, but the figures cover different scopes and should not be used interchangeably.
For those involved in Finland’s franchise market, network-wide turnover is a particularly relevant measure because it includes franchisees. In this case, the company’s turnover alone does not capture the full scale of sales across the network. Equally, total network sales do not, on their own, reveal how profitable the company or an individual franchisee is.
The published figures show that the network as a whole grew year on year. They do not, however, reveal how that growth was distributed among individual franchisees. An increase in the overall figure should therefore not be taken to mean that every business in the network saw the same sales trend.
A franchisee-led project changed the sales mix
Eezy’s EBITDA — earnings before interest, tax, depreciation and amortisation — was €3.1 million in July–September. A year earlier it was €3.7 million, representing a decline of €0.6 million. Turnover growth did not translate into EBITDA growth during the quarter.
According to Arvopaperi, a change in the sales mix contributed to the decline in EBITDA: turnover growth came from a franchisee-led industrial construction project. The issue was therefore not simply how much was sold, but also where those sales came from. This is a key point in the results for readers assessing the franchise market.
However, this information should not be used to draw conclusions about the franchisee’s profitability. The company’s EBITDA and the project franchisee’s earnings are separate matters. The published explanation concerns Eezy’s sales mix and its effect on the company’s EBITDA, not the income statement of an individual franchisee business.
Operating profit, meanwhile, remained at €1.2 million, unchanged from the same period a year earlier. Earnings per share also remained unchanged at €0.00. The third-quarter picture was therefore mixed: EBITDA fell, while operating profit and earnings per share held steady year on year.
It is important to consider these figures alongside one another. A decline in EBITDA is distinct from the trend in operating profit, and a change in one measure does not describe every level of the income statement. In Eezy’s case, sales growth, lower EBITDA and stable operating profit all occurred in the same reporting period.
Staffing services sales grew, but the outlook remained open
Turnover in Eezy’s staffing services business rose to €32.5 million in July–September, compared with €30.8 million a year earlier. The increase of €1.7 million meant that this business also recorded higher sales year on year.
According to chief executive Johan Westermarck, Finland’s economic recovery has progressed, but the labour market has been slower to turn around. In the company’s release, he said employment was not expected to strengthen until 2027. This assessment puts the third-quarter growth figures into a cautious context: rising sales do not yet indicate a broad-based improvement in the labour market.
Westermarck said developments in staffing services had nevertheless been more positive, with temporary staffing turnover returning to growth. This was the chief executive’s assessment of market conditions, not a promise about Eezy’s earnings in future quarters.
Eezy is not providing guidance for 2026. The third-quarter figures therefore describe actual performance, but are not accompanied by a company forecast for full-year earnings. Franchisees and prospective franchisees should distinguish between recorded sales, management’s market commentary and forward-looking guidance.
Financing and profitability complete the growth picture
In April, Eezy carried out a rights issue, raising gross proceeds of approximately €10 million. The aim was to strengthen its capital structure and support the implementation of its strategy. This financing provides context for developments in 2026, but is separate from third-quarter trading turnover or EBITDA.
Overall, Eezy’s results report points to higher network sales and a changed sales mix. Franchisees are included in network turnover, and a franchisee-led project drove growth. At the same time, the company’s EBITDA weakened and it provided no full-year guidance. These findings should be considered together, rather than focusing solely on either growth or weaker profitability.
Practical takeaway: When assessing a franchise network’s finances, examine network-wide turnover, the company’s profitability and the figures for your own franchise business separately. Eezy’s quarter shows that rising total sales alone do not tell you how profitability is developing.